Monetary Literacy & Mastery Foundation

Monetary Literacy & Mastery Foundation

money.forumspark.net

Join the Monetary Literacy & Mastery Foundation to understand how money, banking, inflation, and central banking really work. Free educational resources, community discussions, and structured learning for sound money principles.

24 members 261 topics 1K replies
MoneyMan ·Teaching Resources ·23 hours ago
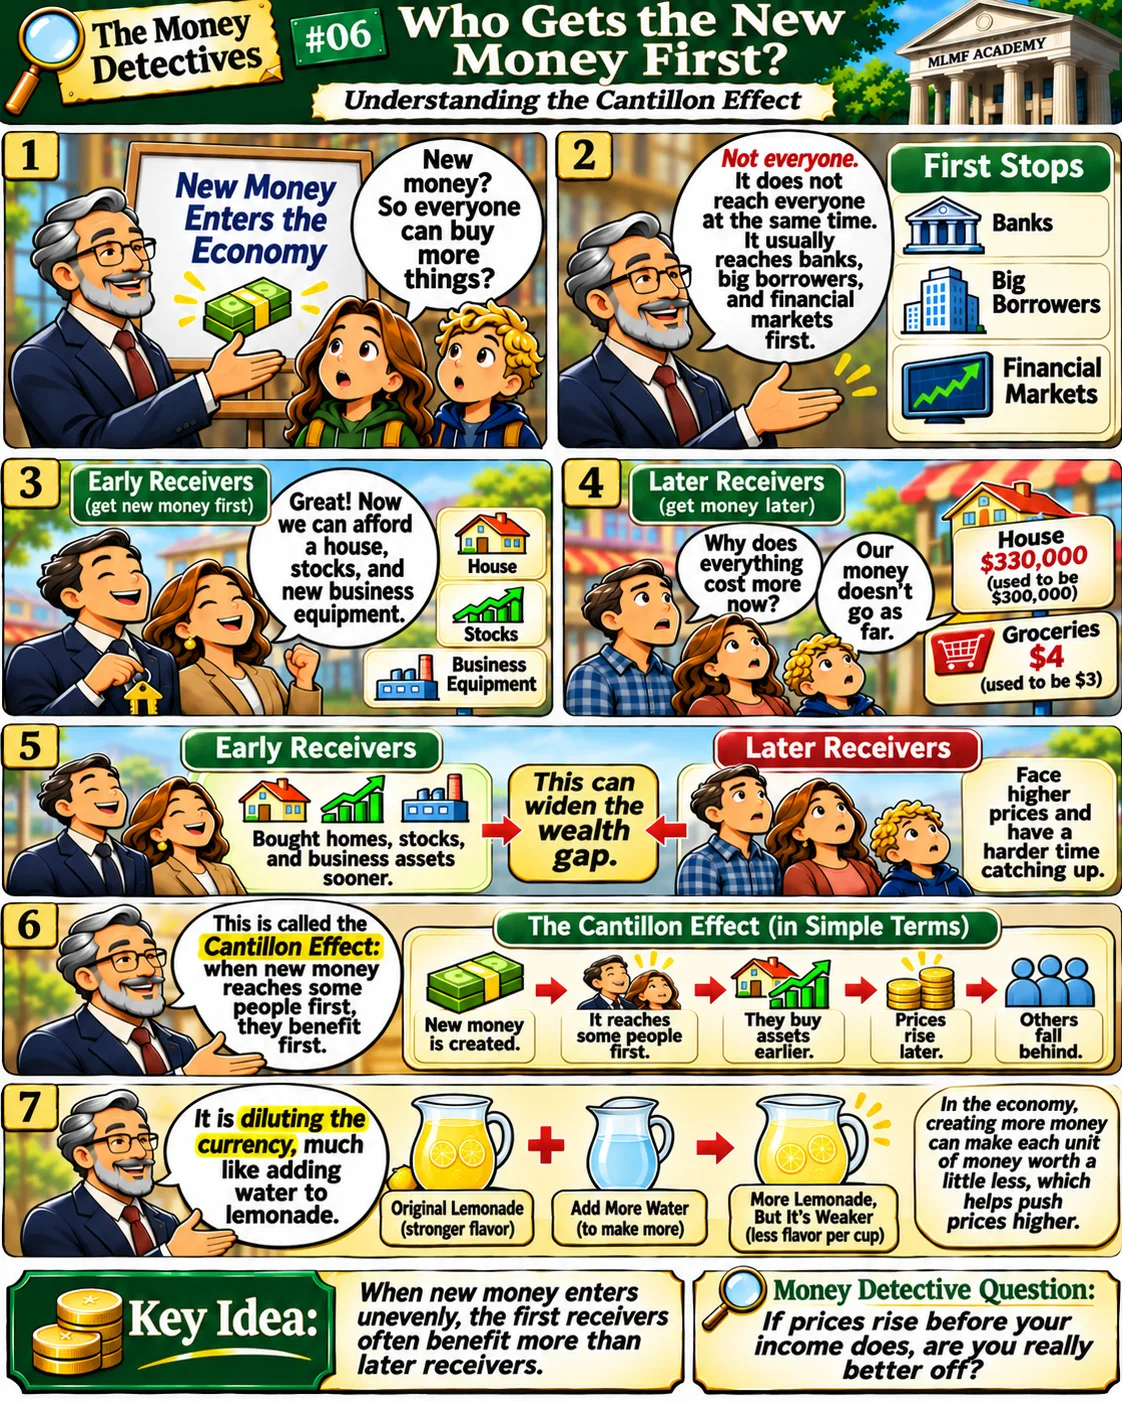
The Money Detectives #06 — Who Gets New Money First?

The Money Detectives #06 — Who Gets the New Money First?

When new money enters the economy, it does not reach everyone at the same time.

This comic introduces the Cantillon Effect—the idea that early recipients of newly created money can spend or invest before prices fully adjust, while later recipients may face higher prices before their own income catches up.

What This Comic Introduces

After reading, learners should understand that:

  • New money enters the economy through specific people, businesses, and institutions first.

  • Early recipients can gain additional purchasing power before prices fully rise.

  • Later recipients may face higher prices before receiving the same benefit.

  • This uneven process can contribute to a wider wealth gap over time.

  • Creating more currency can also dilute its purchasing power—much like adding more water to lemonade makes each cup weaker.

Money Detective Question

If prices rise before your income does, are you really better off?

Encourage learners to think about why the path new money takes through the economy can matter just as much as the amount created.

For deeper study: Continue with MLMF’s lesson on Money Creation & the Cantillon Effect and explore the Cantillon Effect Simulator.
MoneyMan ·Teaching Resources ·1 day ago
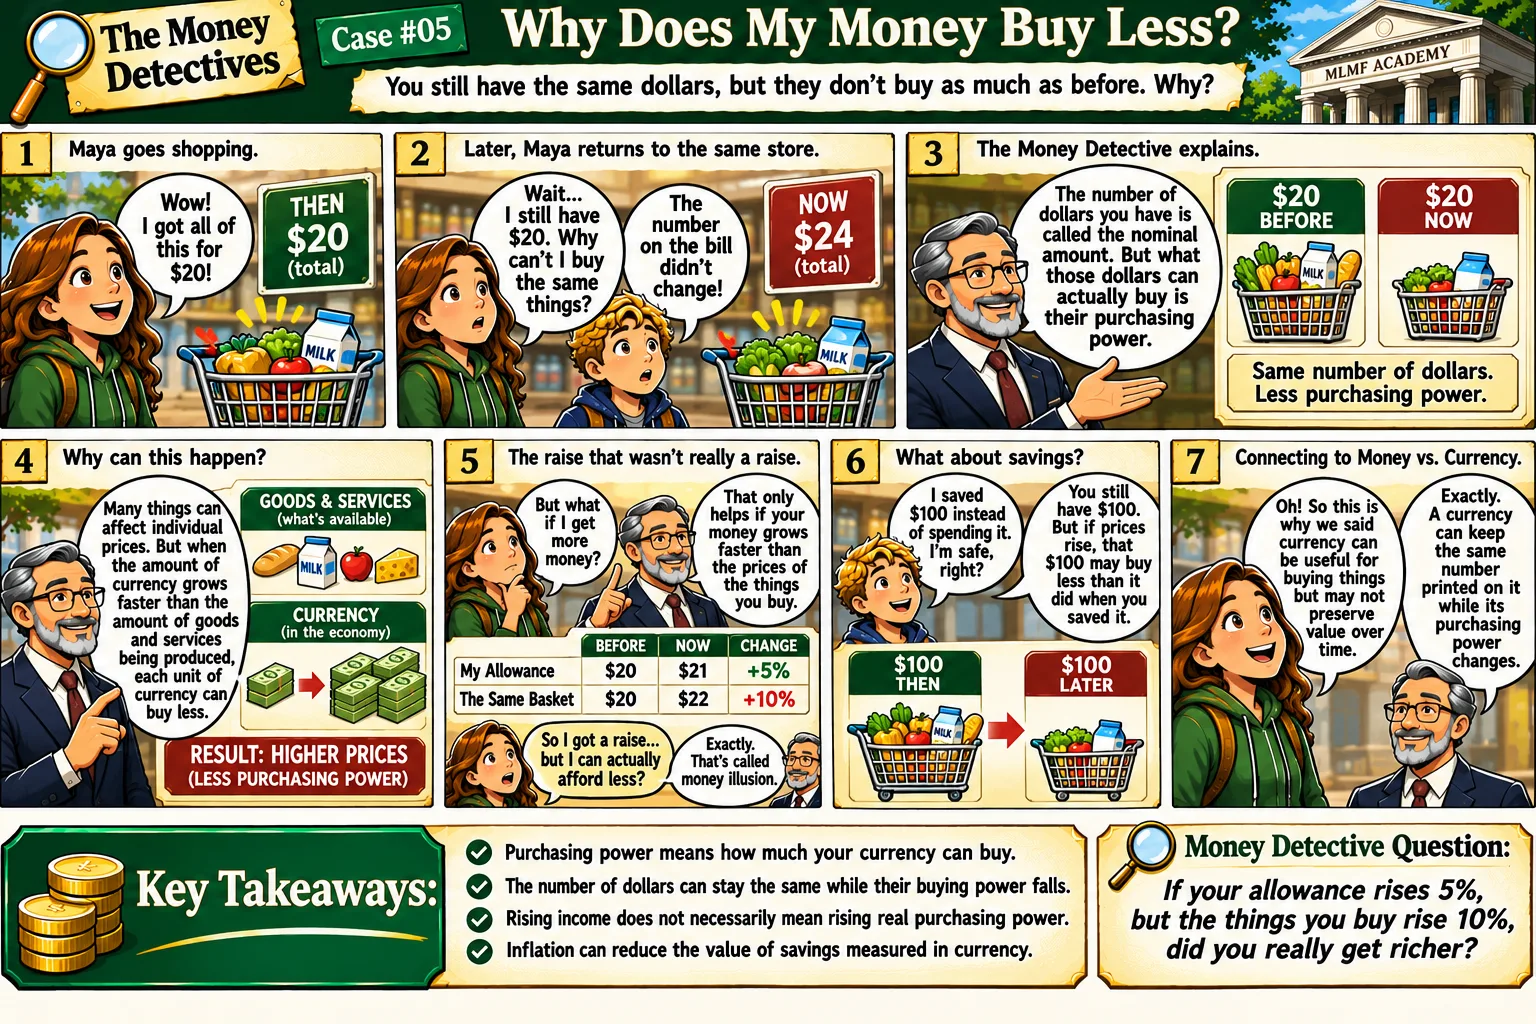
The Money Detectives #05 — Why Does My Money Buy Less?

The Money Detectives #05 — Why Does My Money Buy Less?

You can have the same number of dollars and still be able to buy less with them.

This comic introduces the idea of purchasing power—the amount of goods and services your currency can actually buy. It also shows why a raise in dollars does not always mean a real improvement if prices are rising even faster.

What This Comic Introduces

After reading, learners should understand that:

  • Purchasing power means how much your currency can buy.

  • The number of dollars you have can stay the same while their buying power falls.

  • Rising prices can reduce the real value of wages and savings.

  • A larger paycheck does not always mean greater purchasing power.

  • Inflation can make the same amount of currency buy less over time.

Money Detective Question

If your allowance rises 5%, but the things you buy rise 10%, did you really get richer?

Encourage learners to think about the difference between having more dollars and being able to buy more with those dollars.

For deeper study: Continue with MLMF’s lessons and tools on inflation, purchasing power, and how changes in the currency supply can affect prices.

MoneyMan ·Teaching Resources ·2 days ago
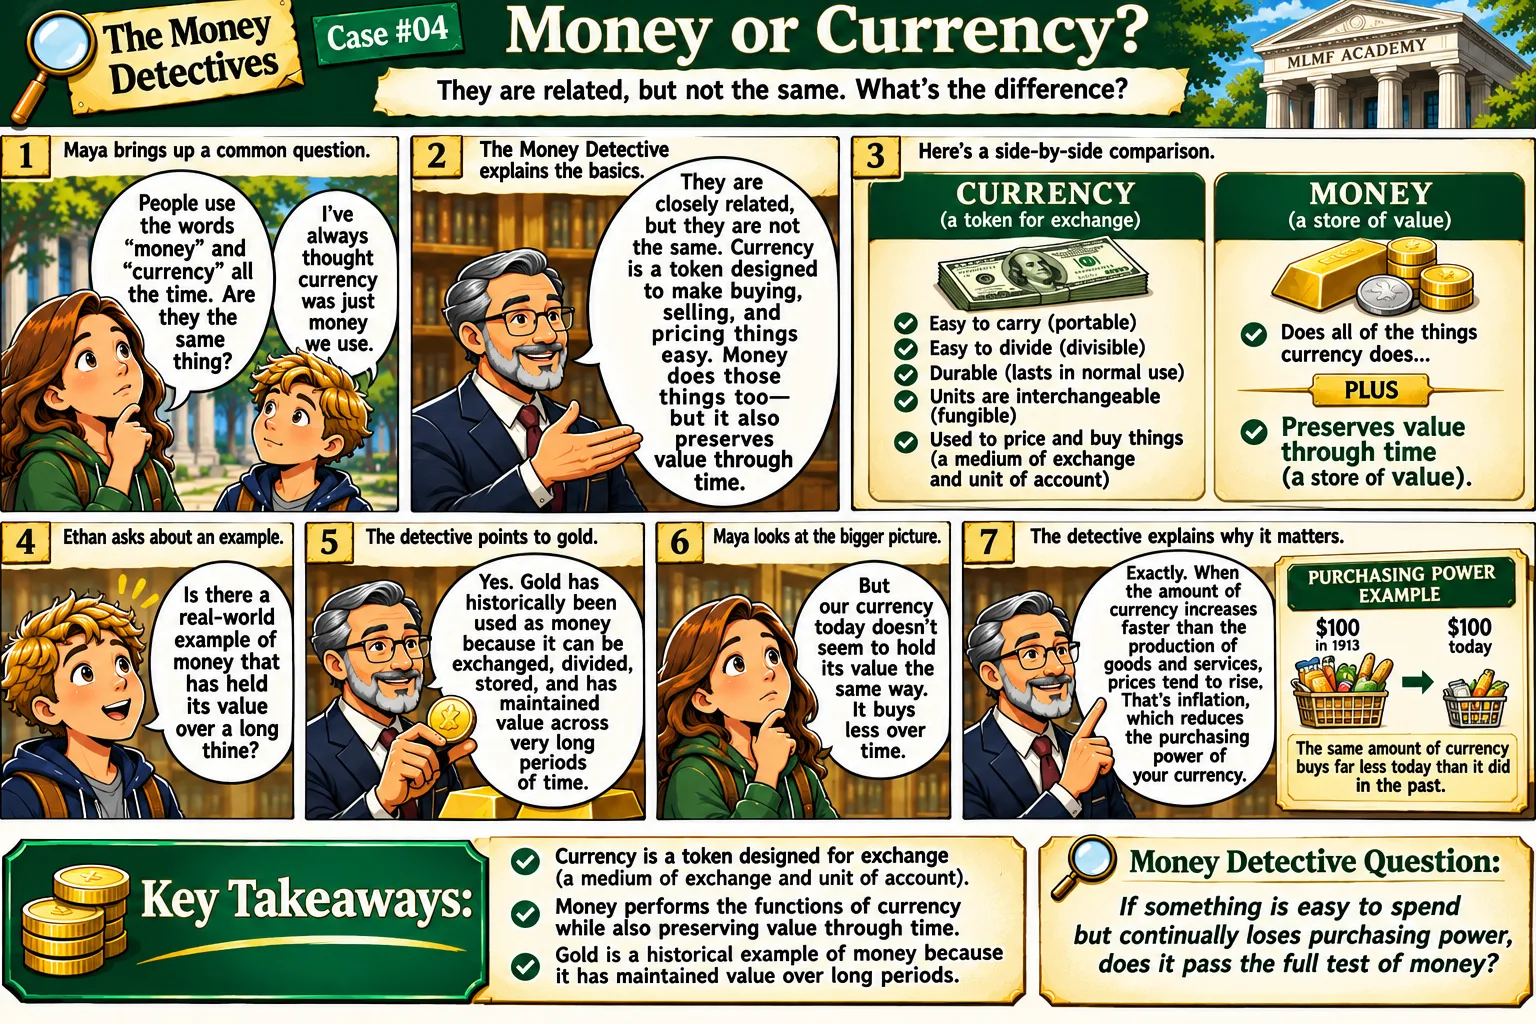
The Money Detectives #04 — Money or Currency?

The Money Detectives #04 — Money or Currency?

People often use the words money and currency as if they mean exactly the same thing. This comic introduces an important distinction.

Currency is designed to make buying, selling, and pricing things easy. It is portable, divisible, durable, fungible, and useful as a medium of exchange and unit of account.

Money performs those functions too—but it also serves as a store of value through time.

What This Comic Introduces

After reading, learners should understand that:

  • Currency is a token designed for exchange.

  • Currency helps us price and purchase goods and services.

  • Money performs the functions of currency while also preserving value over time.

  • Inflation can reduce the purchasing power of currency.

  • Gold has historically been used as money because it has maintained value across long periods.

Money Detective Question

If something is easy to spend but continually loses purchasing power, does it pass the full test of money?

Encourage learners to think about the difference between something that is convenient for exchange and something that preserves purchasing power over time.

For deeper study: Continue with MLMF’s full Money vs. Currency lesson.

MoneyMan ·Teaching Resources ·2 days ago
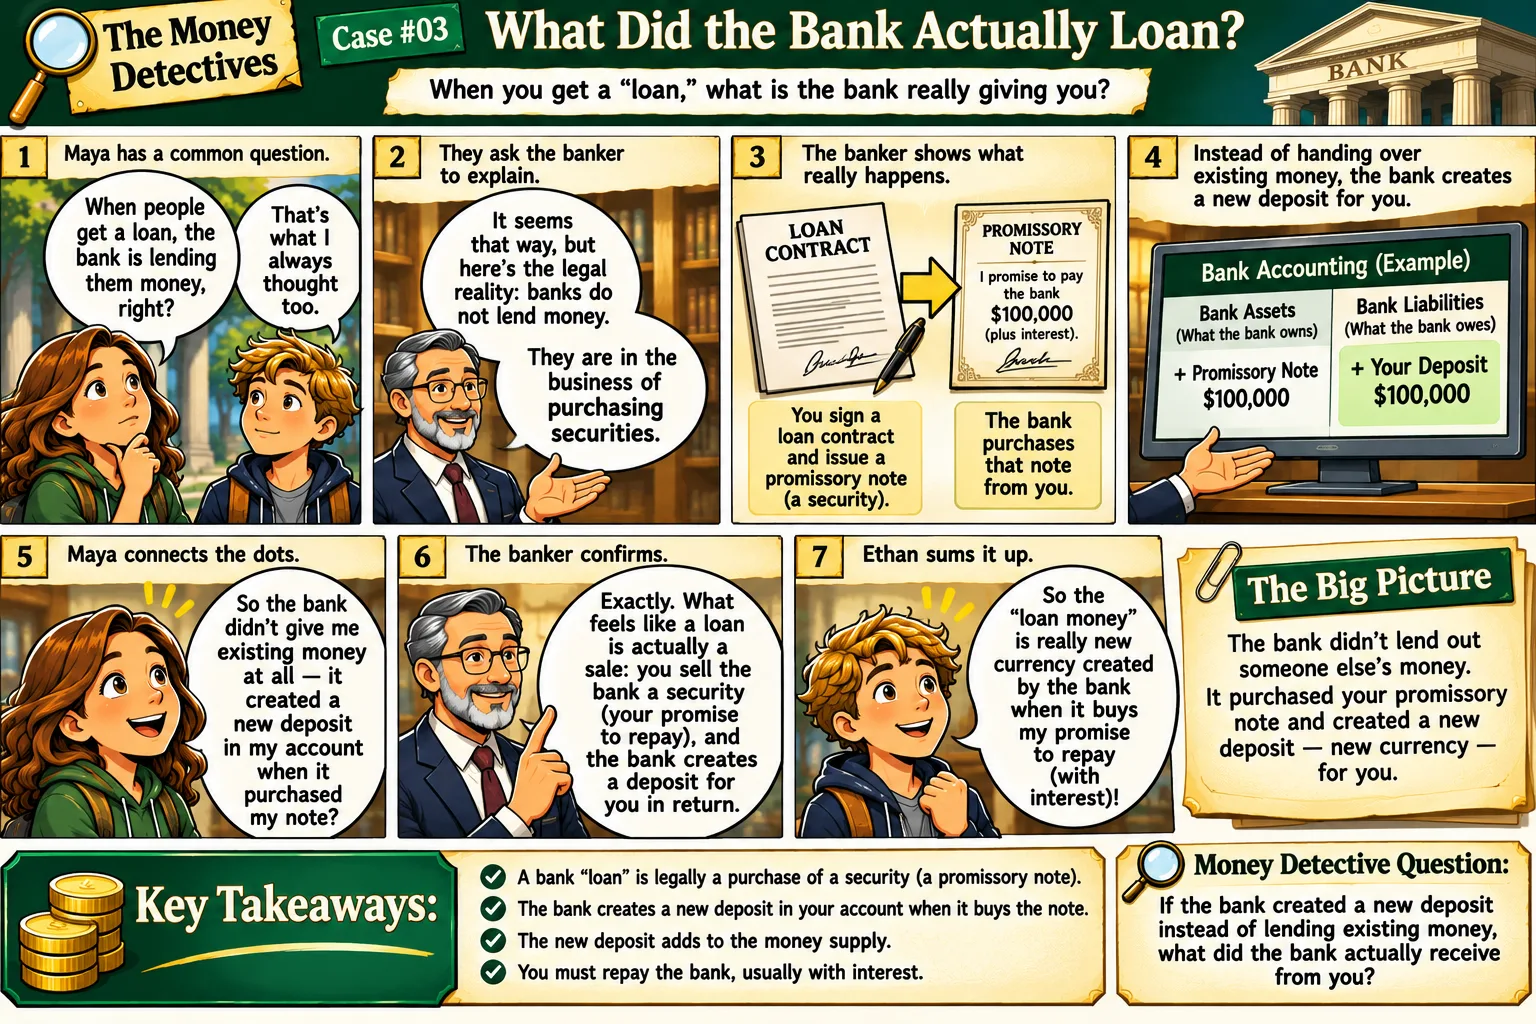
The Money Detectives #03 — What Did The Bank Actually Loan?

The Money Detectives #03 — What Did the Bank Actually Loan?

When someone gets a bank loan, it is easy to imagine that the bank is simply handing over money it already had.

This comic introduces a different way to understand the transaction.

When the borrower signs the loan agreement, the borrower issues a promissory note—a promise to repay. The bank accepts that note as an asset and creates a new deposit in the borrower’s account.

What This Comic Introduces

After reading, learners should understand that:

  • A bank loan is more than simply handing over existing money.

  • The borrower signs a promissory note promising repayment.

  • The bank records that note as an asset.

  • The bank creates a matching deposit in the borrower’s account.

  • The new deposit becomes newly created bank currency.

Economist Richard Werner describes this legal relationship as the bank purchasing a security from the borrower rather than lending out another customer’s deposited money.

Money Detective Question

If the bank created a new deposit for the borrower, what did the bank actually receive in exchange?

Encourage learners to answer in their own words before moving on to the full banking lesson.

For deeper study: Continue with MLMF’s lesson on how bank credit creation works and what happens on the bank’s balance sheet.

MoneyMan ·Teaching Resources ·2 days ago
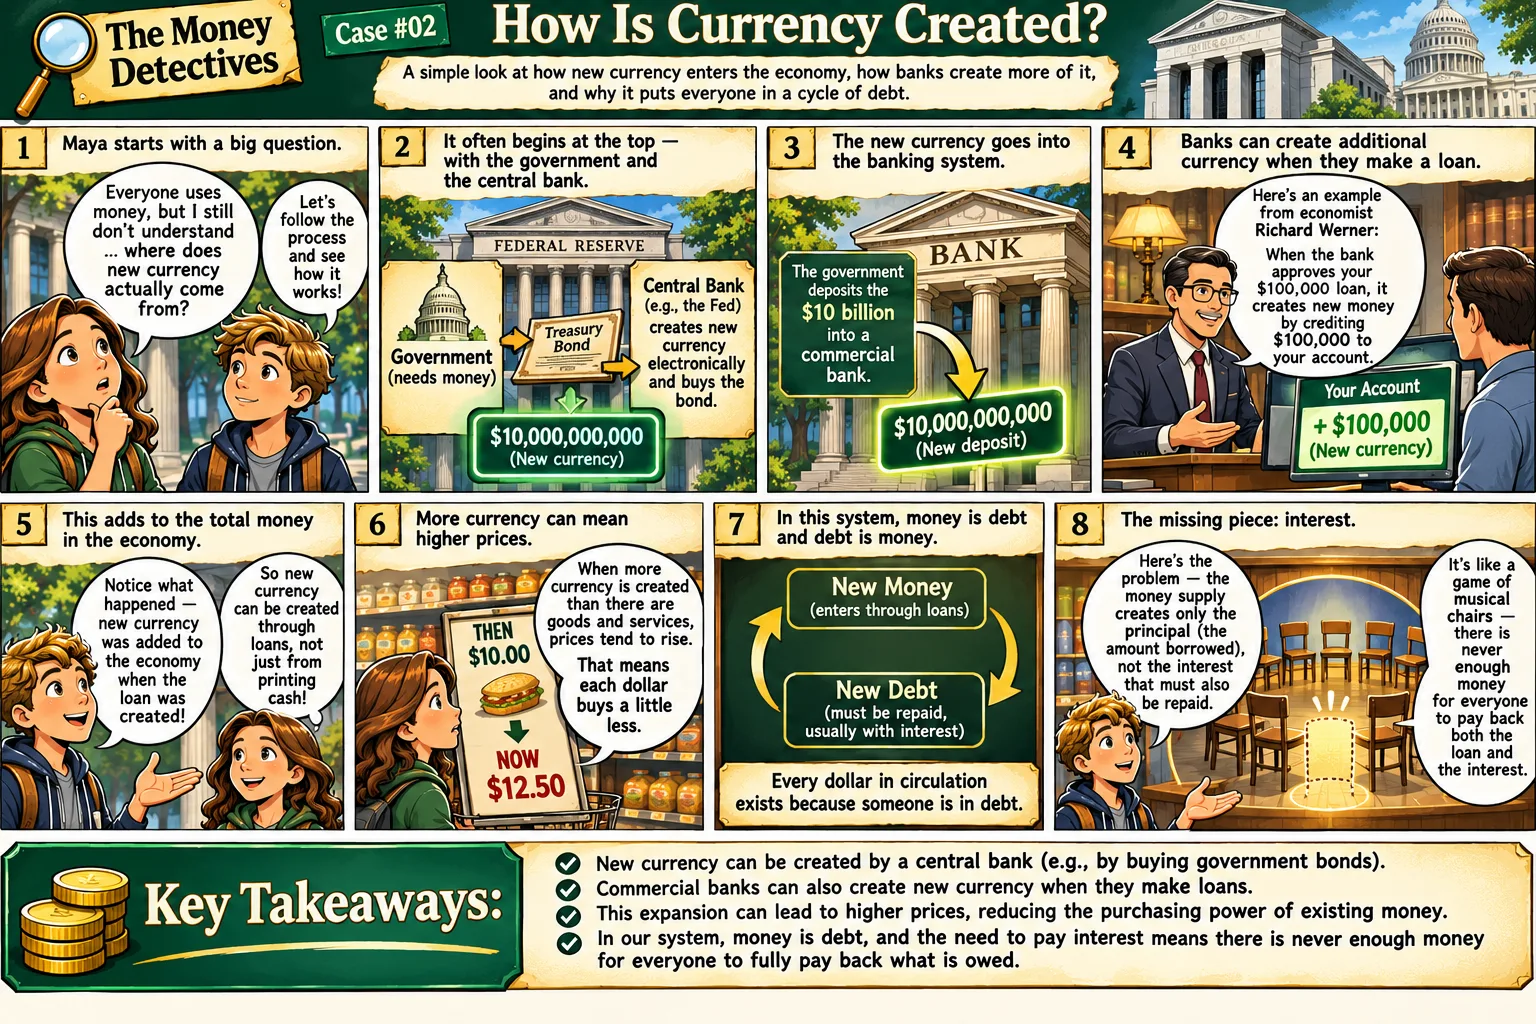
The Money Detectives #02 — How Is Currency Created?

The Money Detectives #02 — How Is Currency Created?

Where does new currency actually come from?

Most people imagine that banks can only lend money that already exists. This comic introduces a different part of the modern monetary system: new bank deposits can be created when a commercial bank makes a loan.

It also introduces how central banks can create new currency when purchasing assets such as government bonds.

What This Comic Introduces

After reading, learners should understand that:

  • Much of the currency used today exists electronically rather than as physical cash.

  • Central banks can create new currency through transactions such as purchasing government bonds.

  • Commercial banks can create new deposit currency when they make loans.

  • The newly created deposit is added to the borrower’s account rather than being transferred from another customer’s deposit.

  • Creating additional currency increases the amount of money circulating through the economy.

Economist Richard Werner has demonstrated this process by following the accounting of an actual bank loan: when a bank approves a loan, it can create a new deposit in the borrower’s account.

Money Detective Question

If the bank did not take the new loan money out of another customer’s account, where did the new deposit come from?

Encourage learners to explain the process in their own words before moving on to the full lesson on bank credit creation.

For deeper study: Continue with MLMF’s lesson on how commercial banks create currency when they make loans.

MoneyMan ·Teaching Resources ·2 days ago
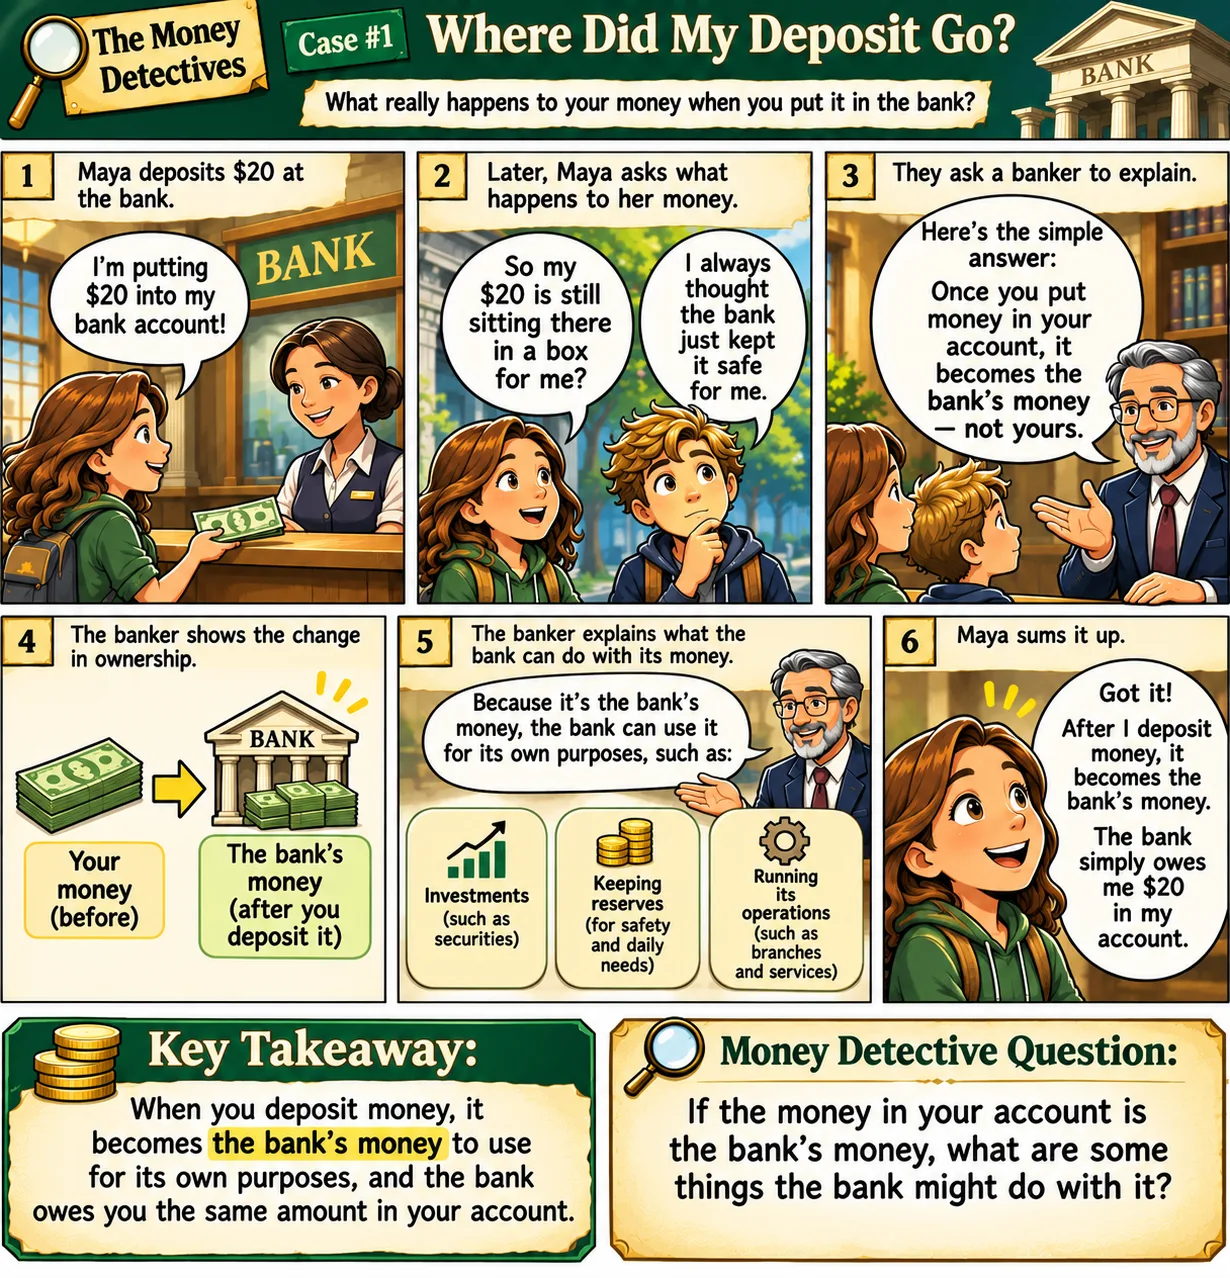
The Money Detectives #01 — Where Did My Deposit Go?

The Money Detectives #01 — Where Did My Deposit Go?

What actually happens when you put money into a bank account?

Many younger learners naturally imagine that the bank simply stores their money somewhere until they come back for it. This short comic introduces a different idea: when money is deposited into an ordinary bank account, it becomes the bank’s money, while the bank records an obligation to repay the depositor.

What This Comic Introduces

After reading, learners should understand that:

  • A bank deposit is not the same as placing money in a personal storage box.

  • The deposited money becomes the property of the bank.

  • The bank records a corresponding amount that it owes the depositor.

  • The depositor therefore holds a claim against the bank.

Money Detective Question

If the money you deposit becomes the bank’s money, what does the balance shown in your bank account represent?

Encourage learners to explain the answer in their own words before continuing to the related banking lessons.

For deeper study: Continue with MLMF’s lesson on why a bank deposit is legally a loan to the bank.

MoneyMan ·Teaching Resources ·2 days ago
Teaching Pack 06: What Do You Actually Own?
Teaching Pack 06

What Do You Actually Own? Understanding Counterparty Risk

Follow the rights, records, and obligations behind a coin, a bank balance, and a brokerage account. Discover who must perform, what protections apply, and how access or recovery can change under stress.

Ages 13–1815-Minute Core ActivityLessons, Books & Documentary
Connecting the Teaching Packs

Look Behind the Account Balance

Pack 02 introduced the deposit as a bank obligation. Pack 05 explored what a dollar amount can buy. Now examine the rights and dependencies behind what you hold.

This activity brings together the banking and securities lessons, the Counterparty Risk Map, and guided reading from David Rogers Webb and Murray Rothbard. It is designed for homeschooling, summer learning, classroom enrichment, and library groups.

01

Identify the Holding

Distinguish physical property, a bank deposit claim, and beneficial share ownership.

02

Trace the Dependence

Identify who keeps the records, owes performance, or controls access.

03

Test the Protection

Match the loss to the relevant protection and investigate its conditions.

Teach With the Cards and Follow the Sources

Use the core activity, then choose a reading or documentary extension.

01

Prepare the Activity

Level: Ages 13–18. The core uses simplified U.S. examples. The securities-law, book, and documentary extensions suit older learners. One adult and one learner can complete the activity.

Prepare: Allow 5–10 minutes. Share student pages 1–3 as reference cards and print pages 4–5 for each learner. Cutting the cards is optional. Use pencil and paper; a connected device is optional.

Read first: Review Banking Lesson 01: Your Bank Deposit Is Actually a Loan and parts 1–3 of Securities Lesson 01: Do You Really Own Your Stocks?. Use the Counterparty Risk Map to revisit the three holding types. The lesson provides the framework; the activity lets learners apply it.

Time: Fifteen minutes for the core. Add 5–10 minutes for assessment, 10 minutes for the shortfall model, or reading/viewing time followed by 15–20 minutes for source work. Do one extension at a time.

“

Ownership, Possession, and a Promise

Owning property, possessing it, and holding a financial claim are different relationships. A coin in your hand needs no bank to release it. A deposit is an amount the bank owes. Brokerage shares involve a beneficial interest held through a custody system.

Ask what you hold, who must act, and what protections apply if something fails. Legal rights can remain valid while access or recovery becomes difficult.

02

Identify, Trace, and Test

0–2 minutes: Read the explanation and predict whether an account balance tells the whole ownership story.

2–6 minutes: Compare the three asset cards and fill the table on student page 4.

6–10 minutes: Choose bank-failure Event 1 or missing-securities Event 2, then price Event 3. Consult the protection cards.

10–14 minutes: Discuss the three questions. Oral answers are fine.

14–15 minutes: Complete the exit sentence.

03

What Is the Legal and Practical Relationship?

Card A · A silver coin you hold

You legally own one genuine silver coin outright and keep it at home. It is fully paid for, not pledged as collateral, and no vault or fund holds it for you.

What is physically in your possession? Does anyone have to repay a debt or deliver the coin to you? Name a risk that still remains.

Card B · A $1,000 bank deposit

You have one ordinary savings account containing $1,000 at an FDIC-insured U.S. bank. You have no other deposits at that bank, no beneficiaries, and no unpaid interest to add.

What does the bank owe you? Are particular banknotes set aside as your property? Which protection card applies?

Card C · Ten shares through a broker

Your cash brokerage account credits you with 10 fully paid shares of a public company, held in street name. The broker is a SIPC member. There is no margin borrowing or securities-lending agreement.

Who records your beneficial interest? Who is named upstream on the issuer record? Which parts of the custody chain must work?

Use the table on student page 4. Identify the property or right, the institution or person whose performance matters, and a risk that remains. The examples are fictional; no real financial information is needed.

Online check: Open the Counterparty Risk Map and compare the Bank Deposit, Securities, and Gold & Silver sections. Record one correction or additional question.

04

What Failed, and What Did Not?

01
The bank fails

The bank in Card B is closed because it cannot meet its obligations. The $1,000 account and its eligibility are correctly documented. Identify the failed obligation and the applicable protection. Does the closure itself establish that the insured $1,000 is lost?

02
Shares are missing

The broker in Card C enters a SIPC liquidation. Records confirm the customer position, but some customer securities are missing. Identify the custody problem. What might restore property, and what extra facts would you need before estimating a final recovery?

03
The price falls

The company remains operating and all 10 shares remain correctly recorded, but their market price falls from $100 to $70 each. Calculate the new value and loss. Has the number of shares changed? Is this the same problem as Event 2?

04
The coin is stolen

The coin in Card A is stolen from its owner. No insurance or other recovery is assumed for this exercise. Name the risk. Did a bank, issuer, or broker fail to repay or deliver the holding? What responsibility came with direct possession?

05

Read the Scope of the Protection

1 · Bank deposits: coverage has a scope

Eligible deposits are insured up to $250,000 per depositor, per FDIC-insured bank, per ownership category. Deposits in the same category at the same bank are combined. FDIC insurance has U.S. government backing; it protects covered dollars, not their future purchasing power.

2 · Broker failure: return of customer property

In a SIPC liquidation, customer property is used to restore customer holdings. SIPC advances can help cover a shortfall, generally up to $500,000 per customer in a separate capacity, including up to $250,000 for cash. Eligibility and the kind of claim matter. Ordinary market losses are excluded.

3 · Shares: rights through a custody chain

The broker records you as beneficial owner. In a typical DTC arrangement, Cede & Co. is the registered holder on the issuer's records. A security entitlement includes rights against the intermediary and a property interest in the relevant pool. Asset-maintenance duties and general customer-priority protections apply, with important statutory exceptions.

Check the current FDIC explanation, SIPC guide, and SEC ownership definitions. UCC 8-503, 8-504, and 8-511 explain the property interest, duties, and priority framework. These are U.S. teaching examples; enacted law and account details matter in actual cases.

Three Questions to Work Through

Use the activity and the relevant lesson to support each answer.

01
How does possessing a coin differ from holding a bank’s promise to repay?

Name the property or right and the party whose performance matters.

02
How does a falling share price differ from missing customer securities?

Identify the loss before deciding whether a protection applies.

03
What would you ask before accepting “It is protected”?

Check the holding, triggering event, limits, and the institution or law behind the protection.

Student Exit Sentence
I hold … I depend on … to … A protection or remaining risk is …
06

Take the Questions Back to the Reading

Choose one route. Allow reading time, then 15–20 minutes for student page 6. Students record the edition and page, paraphrase the argument, apply it, and identify its scope.

Route A · Rothbard: Begin with What Has Government Done to Our Money?, Part I, section 12, Money Warehouses. Read the opening on printed pages 55–58 of the 2024 sixth edition, available through the Mises Institute. Compare the warehouse model with What Actually Happens in Banking Lesson 01.

Ask what a receipt for stored metal represents, what the custodian must do, and how that differs from an ordinary bank deposit. Keeping title to property does not eliminate dependence on someone else who stores it.

Route B · Webb: Begin with The Great Taking, chapter III, Security Entitlement, printed pages 9–15 in version 1.4. The author’s download page provides the edition. Connect it to parts 1–3 of Securities Lesson 01, then compare the general rule and exceptions in UCC 8-503, 8-504, and 8-511.

Ask which mechanism could affect recovery during a shortfall, which conditions must apply, and what further evidence supports a prediction about a widespread crisis. Distinguish the author’s argument from the text of a legal rule. Use the named section if pagination differs.

07

When the Records and the Assets Differ

Use the 300-share / 240-share illustration in the Counterparty Risk Map, then student page 7. Three customers each have a recorded entitlement to 100 shares. Only 240 shares are available.

For the classroom calculation, assume an equal proportional division, no competing claims, and no recoveries or protection payments yet. Find the total recorded amount, the available fraction, the allocation per person, and the shortfall per person.

Then ask: What information would be needed to estimate a final legal recovery? The imposed proportional split illustrates a shortage; it is not a forecast or a complete insolvency calculation.

08

Follow a Claim to Its Evidence

Use Stop It! The Great Taking after the securities lesson. The teacher should preview the film and select an excerpt about custody or legal priority. Allow viewing time separately, then around 15 minutes for the lower half of student page 7.

Record actual start and end timestamps. Paraphrase one claim, connect it to a lesson or book passage, and identify the primary source that supports it. Ask whether the evidence establishes a mechanism, its likelihood, or both.

If the site requests it, activate the video player yourself before using any available chapter controls.

09

Apply It to a New Situation

A. A vault stores a specifically identified silver bar you own outright. It temporarily stops deliveries. Do you have ownership, possession, or both? What risk is shown?

B. Explain why receiving the same dollar balance back may not restore the same purchasing power. Connect your answer to Pack 05.

10

Explain the Relationship and Its Conditions

Asset cards: A is directly possessed property under the stated assumptions. B is a bank repayment claim. C is beneficial share ownership recorded through an intermediary, with a security entitlement that includes legally recognized rights. In a typical DTC arrangement, Cede & Co. is the registered nominee upstream.

Event 1: The documented $1,000 eligible deposit is within FDIC coverage. Bank failure alone does not establish loss of the insured amount. Event 2: Missing securities require examination of customer property, claims, recoveries, and eligible SIPC advances; the final outcome is not specified.

Event 3: Ten shares fall from $1,000 to $700 in total value: a $300 or 30% market loss. All 10 shares remain recorded. Event 4: The loss is physical theft, not failed financial performance under the card’s assumptions.

Shortfall model: 300 shares recorded; 240 available; 80% availability; 80 shares per equal customer; 20 shares short per customer before further recovery. These figures do not determine the final legal payout.

Assessment: A: the customer owns the identified bar but lacks physical possession and depends on the vault for access. B: higher prices can reduce what a fully returned nominal amount buys.

Legal priority: The general protections and statutory exceptions belong in the same explanation. Shortfalls and priority disputes can impair recovery, but beneficial holders are not automatically behind every creditor. Neither registered ownership nor physical possession removes every kind of risk.

Private insurance extension: Policy terms and the insurer’s claims-paying ability matter. Insolvency may produce delays or incomplete recovery; applicable guaranty mechanisms can protect eligible claims within limits. See the NAIC explanation. FDIC and SIPC have distinct frameworks.

11

Download the Student and Teacher PDFs

Use the PDFs attached to this topic. Share the reference cards and give learners their own worksheets.

Student Cards & Worksheets · 7 Pages

Three asset cards; four event cards; protection cards; ownership worksheet; discussion and assessment; two book-reading routes; shortfall model and documentary response.

MLMF-Teaching-Pack-06-Student-Cards-and-Worksheets.pdf

Teacher Guide & Answers · 7 Pages

A 15-minute plan, read-aloud explanation, worked answers, reading guidance, source connections, and protection references.

MLMF-Teaching-Pack-06-Teacher-Guide-and-Answers.pdf

Core printing: Share pages 1–3; print student pages 4–5 per learner. Pages 6–7 are optional extensions. Keep the answer guide separate.

12

Keep the Learning Connected

Banking Lesson 01: Your Bank Deposit Is Actually a Loan

Securities Lesson 01: Do You Really Own Your Stocks?

Counterparty Risk Map

MLMF reading guide: The Great Taking

MLMF reading guide: What Has Government Done to Our Money?

Stop It! The Great Taking - documentary

For further work on incentives, revisit Banking Lesson 03: FDIC Increases Moral Hazard. Return to Teaching Resources for the complete collection. The teacher PDF includes the linked primary texts and current protection references. Prepared November 4, 2026.

1 reply 25 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Teaching Pack 05: When More Dollars Buy Less
Teaching Pack 05

When More Dollars Buy Less Understanding Purchasing Power

A bigger paycheck or savings balance can look like progress. Find out whether it buys more by comparing the numbers with the prices of everyday goods and services.

Ages 13–18 15-Minute Core Activity Worksheets, Simulator & Documentary
The Central Question

Can a Pay Rise Leave You Buying Less?

The dollar amount tells only part of the story. Purchasing power tells us what that amount can buy.

Compare two wage paths in the Purchasing Power Simulator, or use an unchanged shopping basket to test a larger paycheck on paper. Then explore what happens to savings when interest and prices grow at different rates.

Designed for homeschooling, summer learning, classroom enrichment, and library groups. Choose one activity for the short session. Historical data, documentary viewing, and assessment are optional extensions.

01

Look Beyond the Balance

Distinguish the number of dollars from what those dollars can purchase.

02

Compare Pay With Prices

Test whether income and savings keep pace with the same basket over time.

03

Check the Measure

Ask which prices, dates, and households a comparison actually represents.

Teach It Online or on Paper

Choose an activity and use the printable materials attached to this topic.

01

Prepare the Activity

Suggested level: Ages 13–18, introductory. Basic reading and division are enough for the core activity. Percentage calculations are optional. Either route works with one adult and one learner.

Time: Prepare for 5–10 minutes. Allow 15 minutes for one core route, discussion, and an exit sentence. Add 5–10 minutes for savings or assessment, 15–20 minutes for the historical calculator, or viewing and reading time followed by 15–20 minutes for the documentary worksheet.

Online route: Use student pages 1 and 3, a connected device, pencil, and the Purchasing Power Simulator. Enter the starting settings before teaching.

Paper route: Use student pages 2 and 3, pencil, and a calculator. No internet or personal financial information is needed.

Curriculum connection: Pack 03 and Money vs. Currency introduce purchasing power. Pack 04 explores income and price timing. This pack adds measurement, with Nominal Confusion as extended reading.

“

Count What It Buys

The number of dollars is one measurement. What those dollars buy is another. A bigger paycheck can buy less if prices rise faster than pay. A savings balance can grow through interest while losing purchasing power.

To compare fairly, use the same period and the same basket of goods and services. A nominal amount is the number in current dollars. A real amount adjusts for the change in the chosen price measure.

02

Predict, Compare, and Explain

0–2 minutes · Predict.
Can your pay rise while what it buys falls? Record a reason.

2–4 minutes · Introduce.
Read the explanation above and introduce one activity.

4–9 minutes · Compare.
Run A and B online, or calculate what monthly pay and an unchanged $100 can buy on paper.

9–13 minutes · Discuss.
Work through the three questions below. Oral answers are fine.

13–15 minutes · Explain.
Complete the exit sentence and revisit the prediction.

03

Same Prices. Two Wage Paths.

Use student page 1 and open the Purchasing Power Simulator. These are illustrative model inputs.

01
Set Up Run A

Choose Open Laboratory. Set Annual Income to $60,000; Cash Savings to $25,000; Annual Price Inflation to 5%; Annual Wage Growth to 2%; Savings Interest Rate to 1%; and Time Horizon to 10 years.

02
Run and Record

Select Run Purchasing Power Analysis. Record the future nominal income, real income change, cost of the $100 basket, and purchasing power of an unchanged $100. Use end-of-horizon results; set the timeline to year 10 if reading it.

03
Change One Input

For Run B, change only Annual Wage Growth to 5%. Run the analysis again and record the same results. What changed, and what stayed the same?

04
Optional Savings Check

Compare future nominal savings with their purchasing power in today’s dollars. Why do the savings results remain the same in both runs?

Model limits: Constant annual rates, no additional savings contributions or withdrawals, and no taxes or fees. The comparison illustrates a mathematical relationship; it is not a forecast.

04

The Same Basket, a Bigger Paycheck

The fictional example: One year ago, an unchanged basket of goods cost $100. Today it costs $125. Monthly pay rises from $1,000 to $1,100. We compare buying capacity; nobody has to spend the whole paycheck.

Before

Basket price: $100
Monthly pay: $1,000
How many basket-equivalents can this pay buy?

After

Basket price: $125
Monthly pay: $1,100
How many basket-equivalents can the new pay buy?

Calculate: Basket-equivalents = dollars available ÷ basket price. Fractions are allowed: 2.5 means the buying capacity of two and a half baskets. Complete the pay row on student page 2, then compare what an unchanged $100 can buy before and after.

Explain: Has pay increased in dollars? Has its buying capacity increased? Use the quantities to support your answer.

Optional savings: A $500 balance earns 5% interest and becomes $525 over the same year. No deposits or withdrawals are made. Compare the basket-equivalents it buys before and after.

Optional percentage challenge: Calculate the percentage rise in the basket price and the percentage fall in what an unchanged $100 buys. Why are they different?

Assumptions: The basket’s contents and quality stay fixed; taxes and fees are excluded. The price increase is invented and does not establish what caused inflation.

Three Questions to Work Through

Use student page 3 and support your explanation with the activity.

01
How can a larger paycheck buy less?

Separate the dollar amount from what it can purchase. Use one result from your chosen route.

02
What would pay or savings need to do to keep the same purchasing power?

Explain what must match, using the same period and comparison basket.

03
Would every household experience the same change in living costs?

Give one reason and one piece of information needed to compare two households.

Student Exit Sentence
A larger dollar amount does not necessarily mean … To find out whether I can buy more, I need to compare …
05

Check Your Understanding

A. In a new example, the same basket rises from $100 to $110 and pay rises from $1,000 to $1,100. Compare how many baskets each paycheck buys.

B. Prices rose 5% last year and rise 2% this year. Are prices now falling? Explain. Optional: calculate the cost of an initially $100 basket after both years.

06

Compare the Measures

Use student page 4 and the Inflation Calculator. Set Starting Amount to $100, From to 2001, and To to 2024.

Run the calculation for CPI-U, AIER Everyday Price Index, and LISEP True Living Cost. Record each equivalent 2024 amount, cumulative price change, and the date checked.

Read the notes on baskets and populations. This calculator uses January observations for CPI-U and EPI but annual estimates for TLC. Discuss how those differences affect the comparison and which measure may be relevant to a particular household.

Then select M2 Monetary Inflation. Explain why retaining the same proportional share of a money stock is different from buying the same basket of goods. M2 growth is not itself a consumer price inflation rate.

Arithmetic check: For an equivalent amount E, the cumulative price rise is (E ÷ 100 − 1) × 100%. The buying power of an unchanged $100, in starting-year dollars, is 10,000 ÷ E. Apply this check to the price measures.

07

Watch, Read, and Check a Claim

Watch: Hidden Secrets of Money, Episode 1: Money vs. Currency. Preview it before teaching; assign the full film or a checked excerpt. Allow viewing time separately.

Read: In the second post of Nominal Confusion, read What Is Nominal Confusion? and The Real Return Calculation. Allow reading time, then 15–20 minutes for student page 5.

1. Locate: Paraphrase a film claim about storing value or purchasing power. Record actual start and end timestamps. Is it a definition, a historical claim, or a prediction?

2. Test: Which dated prices, wages, or other records could support or challenge the claim? Why can a classroom model alone not establish a historical result?

3. Calculate: A savings balance rises 8% while a comparison basket rises 6%. Calculate (1.08 ÷ 1.06 − 1) × 100% and explain the result.

4. Reconsider: What would you now explain differently about a larger paycheck or balance? Name a question you still want to investigate.

08

Check the Buying Power

Paper route: Monthly pay buys 10 baskets before and 8.8 after. The new pay is worth $880 in starting-year dollars, a 12% real decline despite a 10% nominal rise. An unchanged $100 buys 1 basket before and 0.8 after.

Savings: $500 buys 5 baskets before; $525 buys 4.2 after. The new balance has $420 of starting-year purchasing power, a 16% real decline. The basket price rises 25%, while the buying power of unchanged cash falls 20%.

Simulator, Run A: Independently calculated year-10 income is $73,139.67, worth $44,901.41 in starting-year dollars: a 25.16% real decline.

Simulator, Run B: Income is $97,733.68, worth $60,000 in starting-year dollars: no real change. In both runs, the original $100 basket costs $162.89, and unchanged $100 has $61.39 of starting-year buying power.

Simulator savings: Both runs produce $27,615.55 nominal savings, worth $16,953.55 in starting-year dollars. The teacher PDF gives the formulas. These are calculated expectations for the specified settings; allow for interface rounding.

Discussion: Compare growth in dollars with prices over the same period. Equal growth preserves buying power in the simplified model. Household budgets and price experiences differ; a national index is an average.

Assessment: A: both paychecks buy 10 baskets. B: prices are still rising, just more slowly; this is disinflation. The two-year basket costs $107.10. The documentary calculation gives about 1.89% real growth.

Teaching precision: The exercises show how to adjust a dollar amount for prices. They do not establish a cause of inflation, a historical conclusion, or a forecast. The film and curriculum use a particular distinction between money and currency; standard economics also commonly includes bank deposits within money. Define terms before evaluating claims.

09

Download the Student and Teacher PDFs

The two PDFs attached to this topic are ready to print. Keep the answer guide separate from the learner’s pages.

Student Worksheets · 5 Pages

Online comparison, paper activity, discussion and assessment, historical calculator investigation, and a documentary worksheet.

Filename:
MLMF-Teaching-Pack-05-Student-Worksheets.pdf

Teacher Guide & Answers · 6 Pages

Preparation, a 15-minute plan, read-aloud explanation, worked answers, assessment guidance, adaptations, and sources.

Filename:
MLMF-Teaching-Pack-05-Teacher-Guide.pdf

Print only what you need: Student pages 1 and 3 for the online core; pages 2 and 3 for the paper core. Pages 4–5 and the optional questions are extensions.

10

Continue the Learning

Purchasing Power Simulator · Inflation Calculator

Money vs. Currency · Teaching Pack 04 · Nominal Confusion

Hidden Secrets of Money, Episode 1 connects the activity to the documentary curriculum.

The U.S. Bureau of Labor Statistics CPI questions and answers explains what the CPI covers and why an average measure can differ from a particular household’s experience.

Return to Teaching Resources for the full collection. Prepared September 28, 2026.

1 reply 107 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Teaching Pack 04: Who Receives New Currency First?
Teaching Pack 04

Who Receives New Currency First? Understanding the Cantillon Effect

New currency does not reach everyone at the same time. Follow its path, compare who can spend first, and explore why the order can matter for prices, wages, and purchasing power.

Ages 13–18 15-Minute Core Activity Simulator, Worksheets & Documentary
The Central Question

Does Receiving It First Make a Difference?

The amount of new currency is one part of the story. Where it enters and how it moves can also shape the outcome.

Compare two entry pathways in the Cantillon Effect Simulator, or run a simple paper market in which learners swap who receives currency first. Keep the amount constant and ask what changes.

Designed for homeschooling, summer learning, classroom enrichment, and library groups. Choose one activity for the short session. Documentary viewing, source comparison, and assessment are optional extensions.

01

Trace the Entry Point

Identify who receives new purchasing power first and where spending goes next.

02

Compare the Timing

Explore what happens when prices and incomes adjust at different times.

03

Check the Explanation

Distinguish a result built into a model from evidence about an actual event.

Teach It Online or on Paper

Use the teaching plan, choose an activity, or download the printable materials attached to this topic.

01

Prepare the Activity

Suggested level: Ages 13–18, introductory. Learners need basic reading and division. Percentage work is optional. One adult and one learner can complete either route.

Time: Allow 5–10 minutes to prepare and about 15 minutes for one core activity and discussion. Add 5–10 minutes for the short assessment or the paper activity’s third round and percentage calculations. Allow viewing and reading time separately, followed by 15–20 minutes for the documentary worksheet.

Online route: Open the Cantillon Effect Simulator before teaching. Use student pages 1 and 4, an internet-connected device, and a pencil.

Paper route: Use student pages 2–4, pencils, and scrap paper. Read the role cards or print page 3 single-sided to cut them out. No real money is needed.

Curriculum connection: Monetary Policy, Lesson 5: The Nature of Money Creation – Cantillon Effect. Pack 01 explains loan-created deposits; Pack 02 explains the deposit as a bank obligation; Pack 03 introduces definitions and purchasing power.

“

Currency Reaches People in a Sequence

New currency reaches particular people or institutions before it reaches others. If early recipients spend before some prices adjust, they may buy on different terms from people whose income arrives later.

The entry point and spending path can affect relative prices and purchasing power. This is the central idea we are exploring as the Cantillon Effect. Timing can matter; the result depends on what happens to spending, production, prices, and incomes.

02

Predict, Compare, and Explain

0–2 minutes · Make a prediction.
Ask whether changing who receives currency first could change the outcome. Record a reason.

2–4 minutes · Introduce the activity.
Read the short explanation above, then introduce your chosen simulator or paper activity.

4–9 minutes · Run the comparison.
Compare the two simulator pathways OR complete the first two paper rounds.

9–13 minutes · Discuss the three questions.
Connect receipt order to spending opportunities, price changes, and income timing.

13–15 minutes · Complete the exit sentence.
Revisit the prediction and name one condition that could change the result.

03

Same Amount. Different Entry Points.

Use page 1 of the Student Worksheets PDF, or draw a comparison table on paper.

01
Open the Laboratory

Visit the Cantillon Effect Simulator and choose Open Laboratory. Keep New Money Created at $100 Billion and Money Circulation Speed at Medium. These are model settings.

02
Choose Two Pathways

Scroll to Compare Two Monetary Pathways. Select Financial Markets for Scenario A and Direct Payments for Scenario B. Predict which will affect asset markets earlier and explain why.

03
Run and Record

Select Run Side-by-Side Comparison. Record the first receiver and distribution path in each panel. Compare the asset and consumer channels, then read the explanation beneath the panels.

04
Explain the Difference

What changed even though the new amount stayed the same? What did the model show, and what would need real-world evidence?

Model check: The bars represent simulated relative pressure. They are not measured inflation rates or forecasts. The “Fed” arrows are schematic; they do not mean every commercial bank loan begins with fresh central-bank money or that every government payment creates new money.

04

Who Can Buy What?

The fictional market: The shop starts each round with 20 identical notebooks. Buyers A and B each receive $20, at different times. The first buyer pays $4 per notebook; the second pays $5. Both spend all $20. There is enough stock for both.

Important: These numbers and the price change are invented. The allocations isolate timing; their funding is not modeled. They do not stand for a completed wage payment, asset sale, or bank loan.

Role A · Buyer A

Asset-owning household
Receive an allocation of $20 when the teacher calls your turn. Buy as many identical notebooks as $20 allows at the posted price. Record what you buy. You act first in Round 1 and second in Round 2.

Role B · Buyer B

Wage-earning household
Receive an allocation of $20 when the teacher calls your turn. Buy as many identical notebooks as $20 allows at the posted price. Record what you buy. You act second in Round 1 and first in Round 2.

Role C · Shopkeeper

Business
Begin each round with 20 identical notebooks and no receipts. Charge $4 per notebook to the first buyer. Change the posted price to $5 before the second buyer. Record receipts and notebooks left. Follow the separate rule for optional Round 3.

Role D · Observer

Recorder
Track receipt order, posted prices, purchases, and shop receipts. Check that each buyer receives only $20 per round. Reset everything between rounds. Ask whether a result was observed, calculated, or assumed by the rules.

Round 1: Give A $20. A buys at $4. Change the price to $5. Then give B $20; B buys at $5. Record both purchases, total shop receipts, and stock left.

Round 2: Reset both buyers’ balances, shop receipts, and all 20 notebooks. Reverse the order: B receives and spends first at $4; A receives and spends second at $5.

Optional Round 3: Reset again. A receives and spends before B, but keep the price at $4 for both. Each still receives $20. Does timing produce a purchasing advantage now?

Calculation: Notebooks bought = dollars available ÷ price per notebook. Use the table on student page 2.

For one learner: The adult calls the turns and acts as shopkeeper. The learner records both buyers. The household labels are roles, not fixed predictions: real people can own assets and earn wages.

Optional arithmetic: Calculate the percentage price rise from $4 to $5 and the percentage fall in what the same $20 buys. Why do the percentages differ?

Three Questions to Work Through

Use the activity’s observations and rules to explain your reasoning. Record your answers on student page 4.

01
Who received new purchasing power first, and what could they do with it?

Name the initial recipient in each pathway or round. Explain what earlier access made possible under the stated conditions.

02
What happens to someone whose living costs rise before their income does?

Separate a larger dollar income from the amount of goods and services it can buy.

03
How might the outcome change if businesses produce more goods or wages adjust sooner?

Identify one condition that could reduce, remove, or change the timing advantage.

Student Exit Sentence
Receiving new currency earlier can matter because … One condition that could change the outcome is …
05

Check Your Understanding

A. In your activity, what variable did you change and what new amount did you hold constant?

B. If both paper buyers receive $20 and both pay $4 per notebook, how many can each buy? Is there a timing advantage here?

C. A bank creates a $20 deposit by lending to a borrower. Does the borrower receive a debt-free gift? Explain.

D. Name one real-world observation you would need before claiming that a simulator result explains an actual historical event.

06

Watch, Compare, and Investigate

Watch: Hidden Secrets of Money, Episode 4: The IOU Machine – How Currency Is Created. Preview the film before teaching. Assign the full film or a checked excerpt; allow viewing time separately from the short lesson.

Compare: Read the opening explanation in the Bank of England’s Money Creation in the Modern Economy alongside Pack 01. Compare how the sources explain a bank loan and the creation of a deposit.

Read: In the second post of Nominal Confusion, read “What Is Nominal Confusion?” and “Wages”. Connect the difference between a dollar wage and its purchasing power to the timing question.

Use student page 5 and allow 15–20 minutes after viewing and reading:

1. Film claim: Paraphrase one claim about currency creation or who benefits. Record actual start and end timestamps.

2. Lending check: What does the film suggest happens when a bank lends? Compare this with the Bank of England explanation and Pack 01.

3. Evidence check: What observation, record, or comparison could support or challenge your selected claim? Distinguish an illustration from evidence.

4. Reading application: If living costs rise before wages, why might a later pay rise still leave a household buying less?

5. Your conclusion: What would you now explain differently? Name one unresolved question.

Historical extension: Read Cantillon, Part II, Chapter VI. Identify the early recipients in his mining example and a group whose income adjusts later. Which steps are argued, and which would require evidence?

07

Explain the Result and Its Conditions

Simulator: Scenario A begins with “Financial Markets & Asset Buyers” and displays Fed → Markets → Businesses → Households. B begins with “Households Receiving Payments” and displays Fed → Households. The comparison places more early simulated pressure in financial and asset channels in A. Record current labels if the interface changes.

Round 1 · A Receives First

A buys 5 notebooks at $4. B buys 4 at $5. Shop receipts: $40. Stock left: 11.

Round 2 · B Receives First

B buys 5 notebooks at $4. A buys 4 at $5. Shop receipts: $40. Stock left: 11.

Round 3 · No Price Increase

Both buy 5 notebooks at $4. Shop receipts: $40. Stock left: 10. Timing gives no notebook-buying advantage under these rules.

The Percentage Challenge

The price rises 25%: (5 − 4) ÷ 4. The same $20 buys 20% fewer notebooks: (5 − 4) ÷ 5. The starting quantities differ.

Discussion: Earlier access may allow purchases before some prices rise. Living costs that rise before income can reduce purchasing power. More production or quicker income adjustment can change the outcome. Neither a fixed ranking of winners nor a universal price increase follows from this activity.

Assessment: A: online, the entry pathway changes while the amount stays $100 billion and speed stays Medium; on paper, receipt order changes while each buyer still gets $20. B: 5 notebooks each, with no purchasing advantage from timing here. C: the borrower also owes repayment. D: accept a relevant dated record, such as payments, prices, wages, or output, with an explanation of how it would test the claim. The teacher PDF includes an optional 8-point marking guide.

Film and reading: Look for an accurately located claim, a specific source comparison, testable evidence, and a conclusion that states its conditions. A pay rise smaller than the rise in living costs can leave purchasing power lower. Optional calculation: a 4% wage rise alongside a 5% basket-price rise gives 1.04 ÷ 1.05 − 1, approximately −0.95%.

Teaching precision: Bank lending creates a deposit and a repayment obligation; it does not simply transfer an existing customer deposit to the borrower. Lending remains constrained. Receiving a loan is not a debt-free gift, and an asset seller gives up an asset in exchange for payment. Receipt alone does not establish a net-wealth gain. See the Bank of England explanation.

Model limits: The paper price increase is a rule, not proof that new currency always produces that increase. The shop receives the same funds the buyers spend. “Closer” means access and timing, not physical distance.

Definitions: This pack uses “new currency” broadly for newly created purchasing power, including bank deposits. Central-bank sources usually call these balances deposit money; currency often means notes and coins.

08

Connect the Activity to Its Sources

Curriculum: MLMF Lesson 5: The Nature of Money Creation - Cantillon Effect.

Interactive activity: MLMF Cantillon Effect Simulator.

Documentary: Hidden Secrets of Money, Episode 4: The IOU Machine - How Currency Is Created.

Extended reading: Nominal Confusion: Why Rising Prices Do Not Always Mean Rising Value.

Bank lending and deposit creation: Bank of England: Money Creation in the Modern Economy (2014).

Historical argument: Richard Cantillon: Essay on the Nature of Trade in General, Part II, Chapter VI.

For younger learners: Read aloud, accept oral answers, and count notebooks without percentages.

For older learners: Choose a documented episode, define an outcome and period, and consider supply changes and other explanations before attributing the result to the currency’s entry point.

09

The Printable Materials

Download the Student Worksheets and Teacher Guide attached to this topic. Both are complete materials for Pack 04; no pages need to be extracted from an earlier packet.

Student Worksheets · 5 Pages

Page 1: simulator comparison.
Page 2: paper market and calculation table.
Page 3: four role cards and price signs.
Page 4: discussion, assessment, and exit sentence.
Page 5: documentary and source comparison.

Teacher Guide · 6 Pages

Preparation and the 15-minute plan, simulator setup and interpretation, paper activity answers, discussion and assessment marking, extension guidance, and linked sources.

Print only what you need: Online core: student pages 1 and 4. Paper core: pages 2–4. Add page 5 for the viewing and reading extension. Keep teacher answers separate; print role cards single-sided if cutting.

Continue the Learning Path

Follow the Currency. Then Measure What It Buys.

Next, use the Inflation and Purchasing Power Simulator to explore wages, savings, and changing prices. This leads into the planned Pack 05: When More Dollars Buy Less.

1 reply 106 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Teaching Pack 03: Money vs. Currency—What’s the Difference?
Teaching Pack 03

Money vs. Currency What’s the Difference?

A banknote, a bank balance, a piece of gold, and a debit card can all seem like “money.” But do they perform the same job? Compare how they work today and what they might buy tomorrow.

Ages 13–18 15-Minute Core Activity Worksheets & Documentary Extension
The Central Question

Easy to Spend. Reliable to Save?

Something can work well for payment without preserving the same purchasing power over time.

This activity connects the Foundation’s money-versus-currency lesson to a simple market exercise. Learners identify what each item is, decide how it can be used, and test why a balance or a physical weight does not tell the whole story.

Use it for homeschooling, summer learning, classroom enrichment, or a small-group session. The core activity works on paper. Documentary viewing and the purchasing-power worksheet are separate extensions.

01

Identify What You Hold

Distinguish physical currency, a bank claim, a commodity, and a tool used to make payments.

02

Test Purchasing Power

Compare what an amount can buy instead of relying on its printed number or weight.

03

Compare Definitions

Explain how the curriculum and other sources use the words money and currency.

Teach It Online or on Paper

Read the teaching plan, use the student activity, or download the printable materials attached to this topic.

01

Prepare the Activity

Suggested level: Ages 13–18, introductory. Learners need basic reading and arithmetic. Percentage work is optional.

Time: Allow about 5–10 minutes to prepare. The core session takes around 15 minutes. Add 10–15 minutes for the purchasing-power worksheet. For the documentary extension, allow the full film runtime plus 15–20 minutes for writing and discussion.

Materials: Print pages 1–2 of the Student Worksheets PDF, or read the cards below and write answers on paper. Supply pencils; a calculator is optional. Print single-sided if you want to cut out the cards. No real currency, gold, or account details are needed.

Curriculum connection: Begin with Monetary Policy Lesson 2: Why We Are Confused: Money vs. Currency. Teaching Pack 01 and Teaching Pack 02 provide useful background on deposits, but are not prerequisites.

02

What Do We Mean by Money?

The same word can carry different meanings. Explain which definition is being used before asking learners to classify an item.

Common Economics Usage

Money includes cash and spendable bank deposits. Currency often refers specifically to notes and coins, although people also use the word for a monetary unit such as the dollar.

The Curriculum’s Distinction

MLMF Lesson 2 uses a stricter sound-money distinction, emphasizing the preservation of purchasing power over time. Present this standard explicitly when discussing its conclusions.

Three Functions

Medium of exchange: an accepted way to pay. Unit of account: the unit used to quote prices. Store of value: a way to carry purchasing power into the future.

A Function and Its Performance

Something may serve as a store of value with varying success. Being classified as money does not guarantee constant purchasing power, and physical durability alone does not prove stable value.

Compare the Reserve Bank of Australia’s explanation and the Bank of England’s introduction with MLMF Lesson 2. In Pack 01, “bank-created currency” refers to what central-bank sources call deposit money.

Gold used and widely accepted in exchange is an example of commodity money. In a setting where sellers do not accept it directly, a gold holding serves a different role. Metal prices and purchasing power can change; the CFTC and FINRA guide explains the importance of price changes and costs.

“

Buying Today and Buying Later

Buying something today and preserving spending power for later are different tests. Our market accepts dollars, in cash or through bank accounts. A debit card is a way to use an account. Gold has other uses and a monetary history, but these stalls do not take it directly.

Now ask what each item could buy at a later date. Does its printed number, account balance, or physical weight answer that question by itself?

03

Predict, Compare, and Explain

0–2 minutes · Make a prediction.
Read the fictional market rules below. Ask which card would be easiest to use to buy a $5 notebook and why. Keep the prediction for comparison.

2–4 minutes · Read the four cards.
Read Cards A–D and introduce the three functions. Point out that the debit card accesses the same deposit as Card B.

4–8 minutes · Complete the comparison.
For each card, identify what it is and whether it can pay a stall directly under the stated conditions. Learners can work alone or in pairs.

8–13 minutes · Discuss the three questions.
Compare the pricing unit, the account balance, and purchasing power. Briefly revisit the two uses of “money” in Section 02.

13–15 minutes · Write the exit sentence.
Ask learners to explain the difference between a means of payment and a reliable store of value.

04

Which One Can You Spend Here?

The fictional market: All prices are in dollars. Every stall accepts cash and bank-account payments. None accepts gold directly. Ignore interest and fees. These conditions are part of the exercise, not a claim about every real-world seller.

Predict: Which card would be easiest to use to buy a $5 notebook here? Explain your choice.

Card A · A $20 banknote

You hold a $20 banknote. In this fictional market, every stall accepts it. Prices are marked in dollars. The number printed on the note stays $20; the prices of goods can change.

Think: What does the printed number tell you? What does it leave out?

Card B · A $20 bank deposit

Your account has a $20 spendable balance. Every stall accepts a bank transfer. The balance is the bank's obligation to you. For this activity, ignore interest and fees.

Think: Can you pay without withdrawing notes or coins?

Card C · A small gold piece

You own a piece of gold. None of these stalls accepts gold directly, but a dealer will buy it. Its sale price can change. It has uses as a material as well as a history of monetary use.

Think: Would you need to exchange it before buying something here?

Card D · A debit card

This card accesses the SAME $20 bank deposit on Card B. It is not another $20. A stall can use it to request payment from that account. It does not provide an overdraft in this activity.

Think: Is the card the balance, or a way to use the balance?

Record for each card: Is it cash, a bank claim, a commodity, or a payment tool? Can it pay a stall directly in this market? Explain how, or identify the extra step needed.

Use the comparison table on page 1 of the Student Worksheets PDF, or make the same record on paper.

Three Questions to Work Through

Use the market rules and card details to support your answers.

01
What Is the Unit of Account?

Are the prices measured in dollars, cards, or grams of gold? What tells you?

02
Are You Counting the Same Balance Twice?

Do the bank deposit and the debit card give you $20 or $40 altogether? Explain.

03
Does Acceptance Guarantee Purchasing Power?

Does being easy to spend prove something will preserve what it can buy over time?

Student Exit Sentence
A means of payment and a reliable store of value differ because …
05

Same Amount. Same Buying Power?

Use page 3 of the Student Worksheets PDF. All numbers are invented; they are not historical prices or forecasts. The basket contains exactly the same goods at both dates. Ignore interest, fees, taxes, and selling costs. Treat each example separately.

Earlier: One basket costs $5.
Later: The identical basket costs $6.25.
Calculation: Divide the dollar amount available by the price of one basket.

Cash Kept at Home

Earlier amount: $100.
Later amount: $100.
Calculate the number of baskets at each date.

Bank Deposit Without Interest

Earlier balance: $100.
Later balance: $100.
Calculate the number of baskets at each date.

Gold Holding Sold for Dollars

Earlier sale amount: $100.
Later sale amount: $125.
Does the higher dollar amount buy more baskets?

Change the Sale Price

Suppose the same gold holding instead sells for $75 later. How many baskets could it buy? What does this reveal about an unchanged physical weight?

Stretch question: The basket price rose 25%. Did the $100 balance lose 25% of its buying power? Compare the change in baskets with the original number of baskets.

Extended reading: In the second post of Nominal Confusion, read “What Is Nominal Confusion?” Explain how the numerical exercise illustrates the difference between a dollar amount and what it buys.

06

Watch, Compare, and Investigate

Watch: Hidden Secrets of Money, Episode 1: Money vs. Currency - The Hidden Difference. Preview it before teaching. Allow the full film runtime separately from the 15-minute core, then 15–20 minutes for the viewing worksheet and discussion.

1. Explain the film’s distinction.
What extra quality does it use to distinguish money from currency? Describe the idea in your own words and record a timestamp.

2. Compare the definitions.
Read the opening definition and the section “What forms of money are used in a modern economy?” in RBA: What Is Money?. Compare this with MLMF Lesson 2. How are cash and bank deposits classified? Is the difference about definitions, observable facts, or both?

3. Check a claim about preserving value.
Choose a claim from the film or lesson. What dates, goods or price measure, and evidence would help test it? Would holding or selling costs affect the result?

4. Change the setting.
Imagine a market where gold pieces are widely accepted and prices are quoted in grams of gold. Which functions would gold serve there that it did not serve directly in the first market?

5. Write a careful conclusion.
Finish: “Using ______’s definition, I would call ______ money because …” Then name one question that the evidence has not answered.

Read further: What Is Sound Money? and the Bank of England’s introduction to money. Discuss how a definition, a historical observation, and a prediction require different kinds of support.

07

Check the Reasoning

Prediction: A, B, or D is acceptable if the learner explains how that payment works. “Easiest” depends on circumstances. C requires a further exchange in this market.

Card A: Physical cash; accepted directly.
Card B: A bank deposit, which is a claim on the bank; usable through a transfer.
Card C: A commodity holding; sell or exchange it before paying these stalls.
Card D: A payment tool accessing B’s deposit; it does not add another $20.

Discussion 1: Dollars are the unit of account because prices are quoted in dollars.
Discussion 2: B and D give access to $20 altogether.
Discussion 3: Acceptance today does not establish stable purchasing power later.

Sample exit: “A means of payment lets me complete a purchase; a reliable store of value helps preserve what I can buy later. The first does not guarantee the second.”

Purchasing-power answers: Cash and the deposit each buy 20 baskets earlier and 16 later, a loss of 4 baskets. The gold example buys 20 baskets at both dates: $100 ÷ $5 = 20 and $125 ÷ $6.25 = 20. At the alternative $75 sale price, it buys 12 baskets.

Stretch answer: The price rises 25%, but the $100 amount loses 20% of its basket-buying power: 4 fewer baskets divided by the original 20. The percentages use different starting quantities.

Documentary answers: Look for the emphasis on preserving value over time, a correct account of the RBA’s classification, and a testable claim with a period and purchasing-power measure. Accept different conclusions when the definition and reasoning are clear.

The second market: Gold would serve directly as a medium of exchange, and grams of gold as the unit of account. Whether it preserves purchasing power reliably still needs evidence.

Teaching precision: Physical durability is different from purchasing-power stability. Metal prices can rise or fall; a favorable historical interval does not prove “always.” Judge the stated definition and evidence rather than requiring a particular slogan.

08

Connect the Activity to Its Sources

Curriculum: Monetary Policy, Lesson 2: Why We Are Confused: Money vs. Currency and Monetary Policy, Lesson 3: What Is Sound Money?.

Documentary: Hidden Secrets of Money, Episode 1: Money vs. Currency - The Hidden Difference.

Extended reading: Nominal Confusion: Why Rising Prices Do Not Always Mean Rising Value.

Definitions and modern forms: Reserve Bank of Australia: What Is Money? and Bank of England: Money in the Modern Economy - An Introduction.

Functions and inflation: Federal Reserve Bank of St. Louis: Money and Inflation - A Functional Relationship.

Price variability and costs: CFTC and FINRA: 10 Things to Ask Before Buying Physical Gold, Silver, or Other Metals.

For younger learners: Read the cards aloud, accept oral answers, and use a $20 balance with basket prices of $2 and $2.50. The results are 10 and 8 baskets; percentage work can wait.

For older learners: Compare two documented historical periods. State the selected dates and price measure, account for relevant costs, and explain what the results do and do not establish.

09

The Printable Materials

Download the two PDFs attached to this topic. Both include the materials needed for this pack; you do not need to extract worksheets from an earlier packet.

Student Worksheets · 4 Pages

Page 1: market comparison and discussion.
Page 2: four comparison cards and definitions.
Page 3: purchasing-power calculations.
Page 4: documentary and source-comparison record.

Teacher Guide · 4 Pages

Preparation and the 15-minute plan, core answers, extension answers, source links, teaching precision, and adaptations for different learners.

For the short session: Print student pages 1–2. Keep the teacher answers separate. Print single-sided if cutting out the cards. Add pages 3–4 when you are ready for the extended activities.

Continue the Learning Path

Ask What It Does. Then Ask What It Buys.

A useful explanation identifies the item, names the definition, and examines the evidence. Next, explore how the order in which new currency reaches people can affect their opportunities.

1 reply 132 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Teaching Pack 01: How Bank Lending Creates Currency
Teaching Pack 01

How Bank Lending Creates Currency

When a bank lends $50,000, where does the new account balance come from? Follow the records to discover what is created, who owes whom, and what happens when the loan is repaid.

Ages 13–18 15-Minute Activity 60-Minute Extended Lesson
The Central Idea

The Deposit Is Created with the Loan

The bank creates the spendable balance it lends. That new deposit did not exist before the loan was made.

When a commercial bank makes a loan by crediting an account, it records a new loan and a new deposit together. It does not first have to transfer an equal deposit from another customer.

The borrower owes the bank on the loan. The bank, in turn, owes the account holder the deposit balance. This activity follows both obligations.

A note on terms: In this pack, “bank-created currency” means spendable bank deposits. Central-bank sources often call this deposit money and use “currency” more narrowly for notes and coins. Keep bank deposits, physical cash, and central-bank reserves distinct.

01

Identify What Is Created

Find the new deposit and the matching loan in the bank’s records.

02

Explain Who Owes Whom

Describe the borrower’s obligation to the bank and the bank’s obligation to the depositor.

03

Distinguish a Balance from Wealth

Explain why a larger account balance does not automatically mean greater net wealth.

01

Prepare the Activity

Suggested level: Ages 13–18, introductory. Learners need basic addition and subtraction. Use this as homeschool material, classroom enrichment, a summer learning session, or a small-group activity.

Time: Allow about five minutes to prepare before teaching. The core activity takes approximately 15 minutes. The extended option below brings the session to approximately 60 minutes.

Materials: Paper, a pencil, the student worksheet, and one shared screen with the Commercial Bank Credit Creation Simulator. A calculator is optional. A paper alternative is included below.

Curriculum preparation: Read Banking Fundamentals Lesson 1: Your Bank Deposit Is Actually a Loan, followed by Lesson 2: Whose Money Is the Bank Lending? Open the simulator and practise creating one loan before the session.

The scenario: A repair business borrows $50,000 to buy equipment. Its bank credits a new deposit account. The business has not yet spent the deposit.

Track only this transaction, ignoring fees and interest. The zero starting entries refer to this new transaction, not the bank’s entire balance sheet.

Asset

Something you own or an amount owed to you. The borrower’s deposit is a claim on the bank.

Liability

An obligation you owe. The borrower owes the loan, while the bank owes the deposit.

Principal

The amount borrowed that remains to be repaid, separate from interest and fees.

Net Wealth

Assets minus liabilities. Consider both sides when an account balance increases.

“

Follow Both Sides of the Loan

The bank creates the deposit as part of making this loan. The $50,000 account balance did not exist beforehand. At the same time, the bank records the borrower’s promise to repay.

The borrower has an asset, a claim on the bank, and a debt to the bank. The bank has the loan as an asset and the customer deposit as a liability.

These entries create spending power, but they do not instantly create $50,000 of net wealth for the borrower.

02

Predict, Observe, and Explain

0–2 minutes · Make a prediction.
Ask: “Where will the $50,000 in the account come from?” Have learners write their prediction before explaining the answer. Introduce an asset as something owned or owed to you, and a liability as something you owe.

2–6 minutes · Create one loan.
Open the simulator and select Reset Simulation. Set Loan Amount to $50,000 and Credit Destination to Productive Investment. Select Create Commercial Loan once. Read the loan and deposit entries aloud.

6–8 minutes · Record what changed.
Complete the four records in the student activity below. Compare the new deposit with Existing Deposits Moved and Vault Cash Moved. Ask learners whether their original prediction needs to change.

8–14 minutes · Discuss the three questions.
Allow roughly two minutes per question. Work out the principal repayment in Question 3 on paper; the activity does not require a repayment control in the simulator.

14–15 minutes · Complete the exit sentence.
Ask learners to finish the sentence independently. Check whether they identify the new deposit and the borrower’s debt.

Keep the demonstration focused: The simulator’s asset-pressure and productive-growth percentages are illustrative model outputs. Use its accounting entries for this lesson. Those percentages are not measured effects or forecasts.

Teach it without a screen: Draw two records labeled “Bank” and “Borrower.” Add the entries below, then record $0 for existing deposits moved and $0 for vault cash moved. Ask the learner to explain each entry before completing the worksheet.

The Bank’s Record

Loan receivable: $50,000 asset.
Customer deposit: $50,000 liability.

The Borrower’s Record

Bank deposit: $50,000 asset.
Loan owed: $50,000 liability.

03

Follow a Newly Created Loan

Write your answers on paper or use page 3 of the printable packet.

A repair business borrows $50,000. Its bank credits the business’s account. The business has not yet spent the deposit. Record only this new transaction, leaving out interest and fees.

First, predict: Where do you think the new account balance comes from?

Then, observe: For each record below, write the amount after the bank creates the loan. Keep your original prediction so you can compare it with the results.

Loan Receivable · Bank Asset

Before the loan: $0.
After the loan: $________.

Customer Deposit · Bank Liability

Before the loan: $0.
After the loan: $________.

Existing Deposits Moved

Before the loan: $0.
After the loan: $________.

Vault Cash Moved

Before the loan: $0.
After the loan: $________.

Three Questions to Work Through

Use your recorded observations to support each answer.

01
Was an Existing Deposit Moved?

Did the bank have to move $50,000 from another customer’s deposit to make this loan? What in your record supports your answer?

02
Who Owes Whom?

Who owes whom after the loan? Has the borrower become $50,000 wealthier just because the account balance increased?

03
What Happens on Repayment?

On paper, repay $10,000 of principal from the unspent deposit to the same bank. What are the remaining deposit and loan balances?

Student Exit Sentence
The bank creates ______ when it lends.
The borrower receives ______ and owes ______.
04

Build a 60-Minute Session

Add guided viewing and a purchasing-power exercise to the short activity. Print pages 3 and 6 of the packet, and open the film and readings before the session.

Check the background first: The documentary’s study notes recommend completing Monetary Policy Lessons 1–6. Use the full-film session after that background, or provide guided support for unfamiliar concepts. You can also spread these activities across several days.

0–15 minutes · Complete the core activity.
Follow the short teaching sequence, including the three discussion questions and exit sentence.

15–37 minutes · Watch with a question in mind.
Watch How Our Monetary System Works, listed at 21 minutes, 17 seconds. Record one claim about bank lending or deposits and its timestamp. Save broader unfamiliar claims as questions for later investigation.

37–45 minutes · Check the claim.
Compare it with Banking Fundamentals Lesson 2 and the opening explanation in the Bank of England’s 2014 article. Identify exactly what the sources support, qualify, or leave unanswered.

45–55 minutes · Apply the idea of purchasing power.
Open Nominal Confusion. In the second post, read the section titled “What Is Nominal Confusion?” Complete the basket example below or on page 6 of the packet.

55–60 minutes · Reflect and choose a next question.
Explain how a spendable balance, a debt, and real purchasing power differ. Use evidence from both activities, then keep one unanswered question for the next lesson.

05

Connect the Lesson to the Evidence

Write your answers on paper or use page 6 of the printable packet.

1. Record a documentary claim.
Choose one claim about bank lending or deposits from How Our Monetary System Works. Write it in your own words and note the timestamp.

2. Compare it with a source.
Read the relevant explanation in Whose Money Is the Bank Lending? and the Bank of England article. Identify a passage that supports the claim, limits it, or leaves a question unanswered. Explain your reasoning.

3. Read and calculate.
Read “What Is Nominal Confusion?” in the second post of the Nominal Confusion topic. Then complete this separate, invented example. The contents of each basket stay the same.

Earlier: You have a $100 spending budget. One basket costs $10. How many baskets can you buy?

Later: You have a $120 spending budget. The identical basket now costs $12. How many baskets can you buy?

Compare: Does the larger budget buy more? Show your division or explain in words.

4. Make the connection.
Why are a spendable account balance, a debt, and real purchasing power different things? Use one detail from the loan activity and one from the basket example.

5. Choose your next question.
Write one question you would investigate further. Name a lesson or source that could help you begin.

06

Check Understanding

Expected observations: After one $50,000 loan, the loan receivable is $50,000 and the new customer deposit is $50,000. Existing deposits moved: $0. Vault cash moved: $0.

Question 1 · Was an existing deposit moved?
No equal deposit was transferred from another customer in this transaction. The bank created the new balance when it recorded the loan. The new $50,000 deposit and the $0 transfer entries distinguish creation from moving an existing balance.

Question 2 · Who owes whom?
The borrower owes the bank $50,000 on the loan. The bank owes the account holder $50,000 on the deposit. The borrower’s added asset and added liability offset at origination, so the loan alone adds $0 to net wealth in this simplified example. The deposit is spendable, but it is not earned income or a gift.

Question 3 · What happens on repayment?
After repaying $10,000 of principal from the unspent deposit to the same bank, the remaining deposit is $40,000 and the remaining loan principal is $40,000. Both the bank’s loan asset and its deposit liability decrease by $10,000. The deposit money used for that principal repayment is extinguished.

Exit sentence: Accept equivalent wording: “The bank creates a new deposit when it lends. The borrower receives a spendable balance and owes the loan principal.”

Documentary comparison: Answers depend on the claim selected. Look for an accurate paraphrase, a timestamp, a relevant source passage, and an explanation of what that passage establishes. A learner can identify an unanswered question without having to settle it immediately.

Purchasing-power example: $100 ÷ $10 = 10 baskets. $120 ÷ $12 = 10 baskets. The budget rises 20%, and the basket price also rises 20%, so the larger budget buys the same quantity. This example holds the basket’s contents constant and does not identify the cause of the price change.

Final reflection: A spendable balance is an asset the holder can use for payments. A debt is an obligation to repay. Purchasing power concerns what a balance can buy. In the loan example, the $50,000 balance comes with a $50,000 debt. In the basket example, a 20% larger budget buys no additional baskets.

Learning check: Mark each outcome as secure or revisit: identifies the new deposit; identifies both obligations; calculates the two $40,000 balances. If needed, repeat the relevant step with a $500 loan and a $100 principal repayment. Assess the explanation and evidence.

07

Keep the Explanation Precise

What “lending what it did not already have” means:
The bank issues a new deposit claim on itself. It creates the spendable balance provided to the borrower. This refers to the newly created deposit; the bank still needs resources to operate and meet its obligations.

Creation and settlement are different tasks:
A payment to another bank creates settlement needs. Banks also face capital and liquidity requirements, funding costs, borrower risk, demand for loans, and profitability considerations. The ability to create deposits does not make lending unlimited.

Keep the forms of money distinct:
This activity follows a loan credited to a deposit account. Physical notes and coins, central-bank reserves, and deposits created through asset purchases require separate explanations.

Separate principal from interest:
The repayment exercise concerns principal only. Interest has different accounting treatment. A one-loan example cannot establish that interest payments always require new borrowing.

Use evidence to extend the lesson:
The central-bank resources below describe their own jurisdictions. This worksheet isolates a shared accounting mechanism. Help learners distinguish an explanation of that mechanism from a policy opinion or a country-specific legal rule.

08

Check the Explanation

Use these resources alongside the MLMF curriculum to check the accounting relationships and investigate further questions.

Bank of England · Money Creation in the Modern Economy

McLeay, Radia, and Thomas, 2014. Explains loan and deposit creation, paired balance-sheet entries, lending constraints, and principal repayment.

Bank of England · How Is Money Created?

A short explanation of creation and repayment, including why creating money does not itself create wealth.

Deutsche Bundesbank · How Money Is Created

A 2017 explanation of deposit creation, payment settlement, funding, and the limits on bank lending.

Reserve Bank of Australia · What Is Money?

Distinguishes physical currency from deposits and explains that deposit balances are liabilities of financial institutions.

Support Different Learners

Keep the central accounting relationship the same while adjusting the numbers, reading, or depth of investigation.

01
Younger or Developing Readers

Use $500 and a $100 repayment on paper. Read the explanation aloud and accept spoken answers or labeled drawings. Introduce “owed to” and “owes” before asset and liability.

02
Learners Ready to Go Further

Ask what happens when the borrower pays someone at another bank. Use the Bundesbank explanation to investigate settlement and funding.

03
Home, Group, or Offline Learning

One adult-operated screen is enough. Without internet, use the paper records and teacher notes, then complete the viewing later. Keep the worksheets as a learning record.

09

Use the Curriculum Companion

The seven-page How Bank Lending Creates Currency — Curriculum Companion supplied with this topic contains the printable student worksheets, teaching instructions, answer guide, and source directory.

Use the page numbers below to print the materials needed for your session.

Short Activity · Page 3

Student worksheet with the prediction, four accounting records, three discussion questions, and exit sentence.

Extended Session · Pages 3 and 6

Add the viewing and reading record, purchasing-power calculation, and final reflection.

Teacher Preparation · Pages 1, 2, 4, and 5

Overview, 15-minute teaching instructions, answer key, extended session plan, and adaptations.

Resources & Evidence · Page 7

Linked curriculum lessons, documentary viewing, extended reading, and primary sources.

Continue Learning

Follow the Questions Further

Continue through Banking Fundamentals to explore deposits, lending, and the relationships behind an account balance.

For later documentary study, explore Money as Debt Part II: Promises Unleashed. Schedule it separately from this 60-minute lesson and check the study guidance on its page.

Use the replies below for questions about the activity or feedback from teaching it. Share what helped learners understand, what needed another explanation, and which question you would like to explore next.

1 reply 158 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Teaching Pack 02: Your Bank Deposit Is a Loan
Teaching Pack 02

Your Bank Deposit Is a Loan

When you deposit money, who owes whom? Follow a deposit, a payment, and a withdrawal to discover what your bank balance represents.

Ages 13–18 15-Minute Activity Paper-Based Learning
The Central Idea

Your Balance Records What the Bank Owes You

An ordinary bank deposit creates a creditor relationship: the bank owes the depositor.

When you deposit cash into an ordinary bank account, you receive a claim against the bank. Your account balance records that claim. It does not identify particular notes being stored in your name.

The same deposit is an asset for you because the bank owes you, and a liability for the bank because it must meet that obligation.

This activity develops the other side of the relationship explored in How Bank Lending Creates Currency. Learners take the roles of customers and a bank, then track how those obligations change.

01

Identify Who Owes Whom

Explain why the depositor is the creditor and the bank is the debtor.

02

Read Both Sides

Recognize the same deposit as a customer’s asset and a bank’s liability.

03

Follow the Changes

Track what happens to cash and account balances during a payment and a withdrawal.

01

Prepare the Activity

Suggested level: Ages 13–18, introductory. Learners need basic addition and subtraction. The activity can be used at home, in a classroom, during summer learning, or with a small group.

Time: Allow about five minutes to prepare and approximately 15 minutes for the core activity. Schedule the reading and documentary extensions separately.

Materials: Paper, pencils, and ten paper tokens, each labeled $100. Prepare three record sheets labeled Maya, Alex, and Bank.

Curriculum preparation: Read Banking Fundamentals Lesson 1: Your Bank Deposit Is Actually a Loan. If learners have completed the first teaching pack, ask them to recall why a customer deposit appeared on the liability side of the bank’s records.

The scenario: Maya starts with $1,000 in cash. Maya and Alex have ordinary deposit accounts at the same bank, both initially showing $0. Maya deposits the cash, pays Alex $200 through the bank, and then withdraws $100 in cash.

Keep the model clear: Track only the amounts involved in this exercise. The bank’s zero starting entries do not represent an actual bank’s entire balance sheet. Ignore fees, interest, overdrafts, and other transactions.

Creditor

A person or institution to whom something is owed.

Debtor

A person or institution that owes an obligation.

Asset

Something owned or an amount owed to you.

Liability

An obligation you owe to someone else.

02

Choose Your Roles

Copy these instructions onto separate slips of paper, or read them from the screen. One learner can work through every role with an adult. In a group, assign a different person to each role.

Maya · Customer

You begin with ten $100 cash tokens and a $0 deposit balance. Record your cash separately from the amount the bank owes you.

Alex · Customer

You begin with a $0 deposit balance at the same bank. When Maya pays you, record the amount the bank now owes you.

The Bank

Keep the cash tokens you receive. Maintain separate records of the amounts owed to Maya and Alex. Update those records after each instruction.

The Recorder

After each stage, record the bank’s cash, Maya’s deposit, and Alex’s deposit. Ask each participant to explain what changed.

“

The Bank Is the Debtor

When Maya deposits $1,000 in cash, the bank receives the cash and owes Maya $1,000. Maya’s account balance records that obligation.

Maya is the creditor because the bank owes her. The bank is the debtor because it owes Maya. Maya has not borrowed $1,000 from the bank by making this deposit.

From Maya’s perspective, the deposit is an asset. From the bank’s perspective, that same deposit is a liability.

03

Deposit, Pay, and Withdraw

0–2 minutes · Make a prediction.
Ask: “If Maya deposits $1,000, does the bank owe Maya, does Maya owe the bank, or does nobody owe anything?” Have learners explain their prediction. Introduce creditor and debtor using “is owed” and “owes.”

2–5 minutes · Make the deposit.
Maya hands all ten cash tokens to the bank. The bank records $1,000 in cash and “Owed to Maya: $1,000.” Maya records “Cash: $0” and “Bank deposit: $1,000.” Ask both participants to describe the same deposit from their own perspective.

5–8 minutes · Pay another customer.
Maya instructs the bank to pay Alex $200. Because both customers use the same bank, update the records: reduce the amount owed to Maya by $200 and increase the amount owed to Alex by $200. Leave the cash tokens with the bank.

8–10 minutes · Withdraw cash.
Maya withdraws $100. The bank gives Maya one cash token and reduces the amount owed to Maya by $100. Alex’s balance stays the same. Record the remaining cash and deposits.

10–14 minutes · Discuss the results.
Work through the three discussion questions below. Ask learners to point to the records or tokens that support each answer.

14–15 minutes · Complete the exit sentence.
Let learners finish the sentence independently. Check that they correctly identify the creditor, debtor, asset, and liability.

04

Follow the Bank’s Obligation

Write your answers on paper. Keep a separate record for each stage so you can compare what changed.

Before you begin: Maya has $1,000 in cash. Both customer deposit balances are $0. The bank’s cash tracked in this exercise is $0.

Your prediction: After Maya deposits her cash, who will owe whom? What do you think her account balance will represent?

Record the results: Complete the amounts below as you carry out each stage. At the end, also record how much physical cash Maya holds.

Starting Position

Bank cash: $0.
Deposit owed to Maya: $0.
Deposit owed to Alex: $0.

After the $1,000 Cash Deposit

Bank cash: $________.
Deposit owed to Maya: $________.
Deposit owed to Alex: $________.

After the $200 Payment to Alex

Bank cash: $________.
Deposit owed to Maya: $________.
Deposit owed to Alex: $________.

After Maya Withdraws $100

Bank cash: $________.
Deposit owed to Maya: $________.
Deposit owed to Alex: $________.

Three Questions to Work Through

Explain each answer using the records you completed.

01
Who Is the Creditor?

After the cash deposit, who owes whom? Explain why Maya’s deposit is her asset and the bank’s liability. Has Maya borrowed anything from the bank?

02
What Changed in the Payment?

When Maya paid Alex $200 at the same bank, what happened to each deposit balance? Did the bank hand out any cash? Did its total deposit liability change?

03
What Did the Withdrawal Do?

After Maya withdrew $100, how much did the bank owe each customer? How much cash did Maya hold? Explain what she received in exchange for the reduction in her deposit.

Student Exit Sentence
I am the bank’s ______ because the bank ______ me. My deposit is an ______ for me and a ______ for the bank.
05

Check Understanding

After the deposit: The bank holds $1,000 in cash and owes Maya $1,000. Alex’s balance is $0. Maya holds no physical cash and has a $1,000 deposit asset.

After the payment: The bank still holds $1,000 in cash. It owes Maya $800 and Alex $200. Its total deposit liability remains $1,000.

After the withdrawal: The bank holds $900 in cash. It owes Maya $700 and Alex $200, for a total deposit liability of $900. Maya now holds $100 in physical cash as well as her $700 deposit.

Question 1 · Who is the creditor?
Maya is the creditor and the bank is the debtor. Maya’s deposit is an asset because it is an amount owed to her. It is the bank’s liability because the bank owes that amount. Maya has not taken out a loan from the bank in this activity.

Question 2 · What changed in the payment?
The bank reduced Maya’s deposit by $200 and increased Alex’s deposit by $200. It changed who was owed that amount. No cash left the bank, and the total amount owed to the two depositors stayed at $1,000.

Question 3 · What did the withdrawal do?
The bank repaid $100 of its obligation to Maya in cash. Maya’s deposit fell from $800 to $700, while her cash rose from $0 to $100. Her cash plus deposit still totaled $800 immediately before and after the withdrawal. Alex’s $200 deposit was unchanged.

Exit sentence: “I am the bank’s creditor because the bank owes me. My deposit is an asset for me and a liability for the bank.” Accept equivalent wording that preserves the relationship.

Learning check: Ask the learner to explain the deposit from both perspectives without looking at the role cards. Then ask them to explain why the payment changed two balances while the withdrawal changed both cash and a deposit.

06

Keep the Relationships Clear

A deposit remains an asset for the customer.
Calling a deposit a loan to the bank does not mean the customer has no property or no repayment rights. The customer holds a claim against the bank, rather than ownership of particular notes identified by the account balance.

This cash deposit changes the form of Maya’s money.
Maya gives up $1,000 in physical cash and receives a $1,000 deposit. Do not count the cash now held inside the bank as additional money still held by Maya. This exchange alone has not doubled the public’s spendable money.

A cash deposit and a newly issued bank loan have different matching assets.
In this activity, the bank receives cash and records a deposit liability. In the first teaching pack, the bank records a new loan asset and a new deposit liability. This paper exercise does not establish that banks must receive an equal cash deposit before lending.

The payment stays within one bank.
That is why the activity changes two customer balances without moving cash between banks. Payments involving another bank introduce settlement requirements that can be investigated separately.

The cash totals describe this exercise.
We have not modeled the bank’s lending, investments, other funding, or other customers. The activity therefore does not show a typical bank’s ratio of cash to deposits.

Creditor status and deposit protection can coexist.
Eligible deposits may be protected by deposit insurance, subject to the rules of the relevant country and scheme. For a United States extension, use the FDIC’s explanation of deposit insurance. Protection does not change the basic accounting relationship taught here.

07

Connect the Activity to the Lessons

Read · Banking Fundamentals Lesson 1
Read Your Bank Deposit Is Actually a Loan. Find the explanation of a bank balance as a claim against the bank. Rewrite it in your own words using Maya’s deposit as the example.

Compare · Banking Fundamentals Lesson 2
Continue to Whose Money Is the Bank Lending? Compare a deposit created after a cash payment into the bank with a deposit created when the bank makes a new loan.

Explain the connection: In both cases, what does the deposit represent for the customer? What does it represent for the bank? What asset does the bank record in each case?

Investigate · Payments between banks
Imagine Alex uses a different bank. What additional transaction would the banks need to arrange? Use the Deutsche Bundesbank’s explanation of money creation to investigate the difference between changing customer balances and settling a payment between banks.

08

Examine the Promises Behind the Balances

For a later session, watch Money as Debt Part II: Promises Unleashed, the documentary linked from Banking Fundamentals Lesson 1.

Plan the viewing: The film is listed at 1 hour, 16 minutes, 45 seconds, with the banking lessons 1–3 recommended beforehand. Schedule the full film separately from the 15-minute activity. A teacher can also preview it and select a relevant excerpt, recording the chosen start and finish times.

Before watching: Write one sentence explaining what Maya owns after depositing her cash and who owes the corresponding obligation.

During viewing: Record one claim about deposits, bank obligations, or the creation of bank money. Write the claim in your own words and note its timestamp.

After viewing: Compare that claim with the relevant curriculum lesson and one of the primary sources below. Identify a passage that supports it, qualifies it, or leaves a question unanswered.

Written reflection: “What does a bank balance promise, and how did our deposit, payment, and withdrawal activity help me understand that promise?” Use one example from the activity and one detail from your reading or viewing.

Teacher review: Look for an accurate description of who owes whom, a specific example, and a relevant source passage. Assess the learner’s reasoning and evidence, rather than agreement with every argument in the documentary.

09

Check the Explanation

Use these sources to check the meaning of a deposit and to distinguish the accounting relationship from questions about regulation, protection, or policy.

Bank of England · Money in the Modern Economy

A 2014 introduction explaining money as a form of IOU and distinguishing currency, bank deposits, and central-bank reserves.

Reserve Bank of Australia · What Is Money?

The section on modern forms of money identifies deposit balances as liabilities of financial institutions.

Deutsche Bundesbank · How Money Is Created

Further explanation of deposits, lending, and the funding needed to settle payments.

FDIC · Understanding Deposit Insurance

A United States resource explaining protection for eligible deposits at insured banks and the conditions of coverage.

Support Different Learners

Keep the relationships the same while adjusting the numbers or depth of discussion.

01
Younger Learners

Use ten $10 tokens: deposit $100, pay $20, and withdraw $10. Begin with “the bank owes me” before introducing creditor and liability.

02
Independent Learners

Keep separate pages for the bank and each customer. Explain every change aloud before checking the answer guide.

03
Further Investigation

Explore how payments work across different banks, or research which deposit protections apply in your country using an official source.

Continue Learning

Look at Both Sides of the Balance

Each time you see an account balance, ask: whose asset is this, whose liability is it, and what transaction created or changed it?

Use the replies below for questions about the activity or feedback from teaching it. Share which step helped learners understand the relationship and which questions they would like to investigate next.

1 reply 141 Read more →
MoneyMan ·Teaching Resources ·1 month ago
Start Here: Using the Teaching Resources
Parent & Teacher Guide

Start Here: Using the Teaching Resources

Practical activities, guided discussion, and further learning for homeschooling, classroom enrichment, and group learning.

HomeschoolingClassroom EnrichmentGroup Learning
Begin Here

Welcome to the MLMF Teaching Resources

This section helps parents, educators, and group leaders teach monetary literacy through practical activities, guided discussion, and further learning.

The materials connect directly to the Monetary Literacy & Mastery Foundation's existing curriculum, documentaries, simulators, and extended studies.

Use them alongside your current schooling, as part of a homeschool program, or for a summer learning session, economics club, or library workshop.

01

Prepare

Choose a suitable topic, read the teacher notes, and gather the materials before beginning.

02

Teach

Guide learners through an activity, discuss their observations, and check their understanding.

03

Explore

Continue through the related curriculum lessons, documentaries, simulators, and extended reading.

01

Who These Materials Are For

The lesson packs are designed for parents teaching at home, teachers adding enrichment activities, and facilitators working with small groups. Independent learners can also use the activities to check their understanding.

Check each pack's suggested age, difficulty, and prerequisite knowledge before beginning. The teacher notes will help you prepare the explanation and adapt the activity to your learners.

02

What You Will Find in Each Topic

Each lesson-pack topic will bring together the teaching materials for one concept:

Lesson Overview

Learning goals, suggested level, estimated teaching time, and materials needed.

Parent or Teacher Guide

A short explanation and instructions for leading the activity.

Student Materials

A worksheet, practical exercise, or guided simulator investigation.

Discussion and Review

Questions, suggested answers, and a brief check of understanding.

Further Learning

Relevant curriculum lessons, documentary viewing, extended reading, and supporting sources.

Printable Downloads

Student sheets and teacher notes for use away from the screen.

“

Encourage Questions and Evidence

Ask learners to explain their reasoning, identify the assumptions in an example, and check claims against the linked sources.

When a documentary or article presents an interpretation, discuss the evidence supporting it and what further information would help assess it.

The aim is for learners to understand the mechanisms well enough to explain them, ask informed questions, and investigate further.

“

A Perspective, Not a Required Conclusion

MLMF approaches monetary education from a monetary-systems-first perspective, with particular attention to legal and institutional mechanics, monetary history, and questions raised by the sound-money tradition.

Educators are encouraged to use the material as a basis for examination, comparison, and discussion rather than requiring learners to adopt a particular conclusion.

Read Our Approach & Editorial Principles →

03

How to Use a Lesson Pack

1. Choose a topic and prepare.
Read the overview and teacher notes. Check the recommended background reading, gather the materials, and open any simulator or video you plan to use.

2. Begin with the opening question.
Ask learners what they think happens before explaining the concept. Keep their predictions so they can compare them with what they discover.

3. Complete the activity.
Follow the instructions and record the results. Encourage learners to explain what changed and why. Use the paper alternative when one is provided.

4. Discuss and review.
Work through the questions together, then let learners complete the short understanding check independently. Use the answer guide to identify anything that needs another explanation.

5. Continue learning.
Follow the linked lesson, documentary, or extended reading. Each suggested extension will include a question or task to give the reading or viewing a clear purpose.

Choose the Time You Have

Use the format that suits your learners and the time available.

01
A Short Session

Begin with the core activity, typically designed for around 15 minutes. Allow preparation time beforehand.

02
A Longer Session

Add discussion, reading, or documentary viewing. Extended sessions will generally run around 45–60 minutes; check the individual pack's schedule.

03
Several Sessions

Spread the activity, documentary, and follow-up reading across different days. Move on when learners can explain the central idea in their own words.

04

How This Connects to the Rest of MLMF

The teaching packs provide a practical way to work through material across the Foundation:

Money Mechanics provides the core lessons to read alongside the activities.

Interactive Simulators let learners change inputs and examine the results within a model.

Documentary & Video provides material for guided viewing and discussion.

Extended Studies offers further reading and questions to investigate.

Each pack will identify the specific resources that support its activity, so you can follow the connections directly.

05

Using MLMF Material With Students

Educators, parents, and nonprofit learning groups are welcome to use MLMF material for ordinary noncommercial educational purposes.

Link to MLMF Resources

You may link directly to MLMF lessons, articles, simulators, documentaries, and teaching resources.

Display During Instruction

You may display MLMF pages, tools, and resources during classroom, homeschool, workshop, or group instruction.

Assign for Student Use

You may assign MLMF material for student reading, viewing, discussion, or independent study.

Print for Noncommercial Use

You may print reasonable quantities of MLMF material for students or participants in a noncommercial educational setting.

Quote With Attribution

You may quote reasonable excerpts when attribution to the Monetary Literacy & Mastery Foundation is retained.

Please Contact Us Before Republishing

Please contact the Foundation before reproducing complete lessons or Teacher Packs elsewhere, republishing substantial portions online, or incorporating MLMF material into a commercial product or publication.

Attribution: When distributing printed excerpts or reproduced material, please retain attribution to the Monetary Literacy & Mastery Foundation and, where practical, include the original page address.

Our First Lesson Pack
Lesson packs are being added to this section. The first pack focuses on How Bank Lending Creates Currency.
Support and Discussion

Questions or Feedback

Use the replies below for general questions about the teaching resources. For questions about a particular activity, reply in that lesson-pack topic.

If you use a pack, tell us what worked, what needed clarification, and which concepts you would like to teach next.

ForumSpark © 2023 - 2026 · ForumSpark.net · Terms